Capstone Metals — gold and silver IRA dealer
Speak with a specialist: (800) 200-9553Monday – Friday, 7am – 4pm Pacific

Reserve preferences and purchasing power

What Happens When Reserve Preferences Change?

De-dollarization is not one event. It is five measurable things: how central banks hold reserves, how trade is invoiced and settled, which payment systems are used, whether households and firms substitute currencies, and whether official gold holdings are rising. Most headlines describe one of them and imply all five. This page separates them, shows what the data records, and says where the evidence runs out.

Monday – Friday, 7am – 4pm Pacific. Call or text (800) 200-9553.

  • Education only — no product offer on this page
  • IMF, BLS and Federal Reserve data, cited with dates
  • Non-partisan: the question is monetary, not political
  • Forecasts labelled as forecasts, never as facts
  • Counter-evidence included by design

Read the Evidence Guide

Educational material. No obligation, and no purchase involved.

By submitting your name and phone number you are asking us to follow up, and you agree that Capstone Metals may contact you by phone, text, or email to clarify what you are looking for and make sure you receive it. Message and data rates may apply. You can ask us to stop at any time by replying STOP or telling us on the phone, and we never sell or share your information. This is a request for information and a conversation — not a purchase, an application, or advice. SMS Opt-In Policy · Privacy Policy · Terms & Conditions · How pricing works · Disclosures · Due diligence & financial risks

What happens next: we send the guide. If you would like a conversation, you can ask for one — we will not push a retirement-account offer onto a research request.

Established 2014 — licensed and insuredAdvisory under licensing held since 1970Independent custodians: Preferred Trust, GoldStarACH or wire funding — no card payments

At a glance

Dollar reserve share

Gradual, decades-long drift lower

IMF COFER records the currency split of allocated official reserves. The dollar's share has drifted down over two decades and remains the largest by a wide margin.

International Monetary Fund Quarterly series

Purchasing power

Measurably lower over time

The BLS Consumer Price Index series records how much less a dollar buys. It measures one basket and has changed methodology over time.

U.S. Bureau of Labor Statistics Monthly series

Official gold

Central banks have been net buyers

Reported official-sector buying in recent years. The compilation most often quoted comes from the World Gold Council, an industry body.

World Gold Council 2025 · industry-funded source

Settlement alternatives

Growing from a small base

Alternative payment and settlement arrangements exist and are expanding. Announcements are more numerous than measurable volumes.

Federal Reserve Board Current

What this evidence does not show: that the dollar is losing reserve-currency status, that any replacement currency exists, or that any dated prediction of dollar failure is supported. It also does not show that gold or silver will preserve purchasing power — that is a separate question with a mixed record.

Five different questions, asked separately

  1. 1. Reserve composition

    What currencies central banks actually hold. Measured quarterly by the IMF for allocated reserves. This is the slowest-moving and best-measured layer.

  2. 2. Trade invoicing and settlement

    Which currency a shipment is priced and paid in. Bilateral local-currency arrangements have grown, and most are small relative to global trade.

  3. 3. Payment systems

    The plumbing: correspondent banking, messaging networks and alternatives. Announcements here are frequently reported as if they were reserve changes. They are not.

  4. 4. Currency substitution

    Whether households and firms hold or transact in another currency by preference. Usually a symptom of domestic instability rather than of global reserve shifts.

  5. 5. Gold accumulation

    Whether official reserves are being diversified into an asset with no issuer. Reported buying has been consistent in recent years, and the reasons stated by reserve managers vary.

Start with the thing that is actually measured

Before reserve currencies, there is a simpler and better-documented question: what does a dollar buy? The Bureau of Labor Statistics publishes the Consumer Price Index, and the erosion of purchasing power over decades is not in dispute. That is a measurement, not an opinion.

Its limits belong with it. CPI tracks one basket, methodology has changed over time, and the inflation an individual household experiences depends on what it buys — housing, tuition and medical care have behaved differently from consumer goods. The chart tells you what a dollar bought. It does not tell you what any asset will do next.
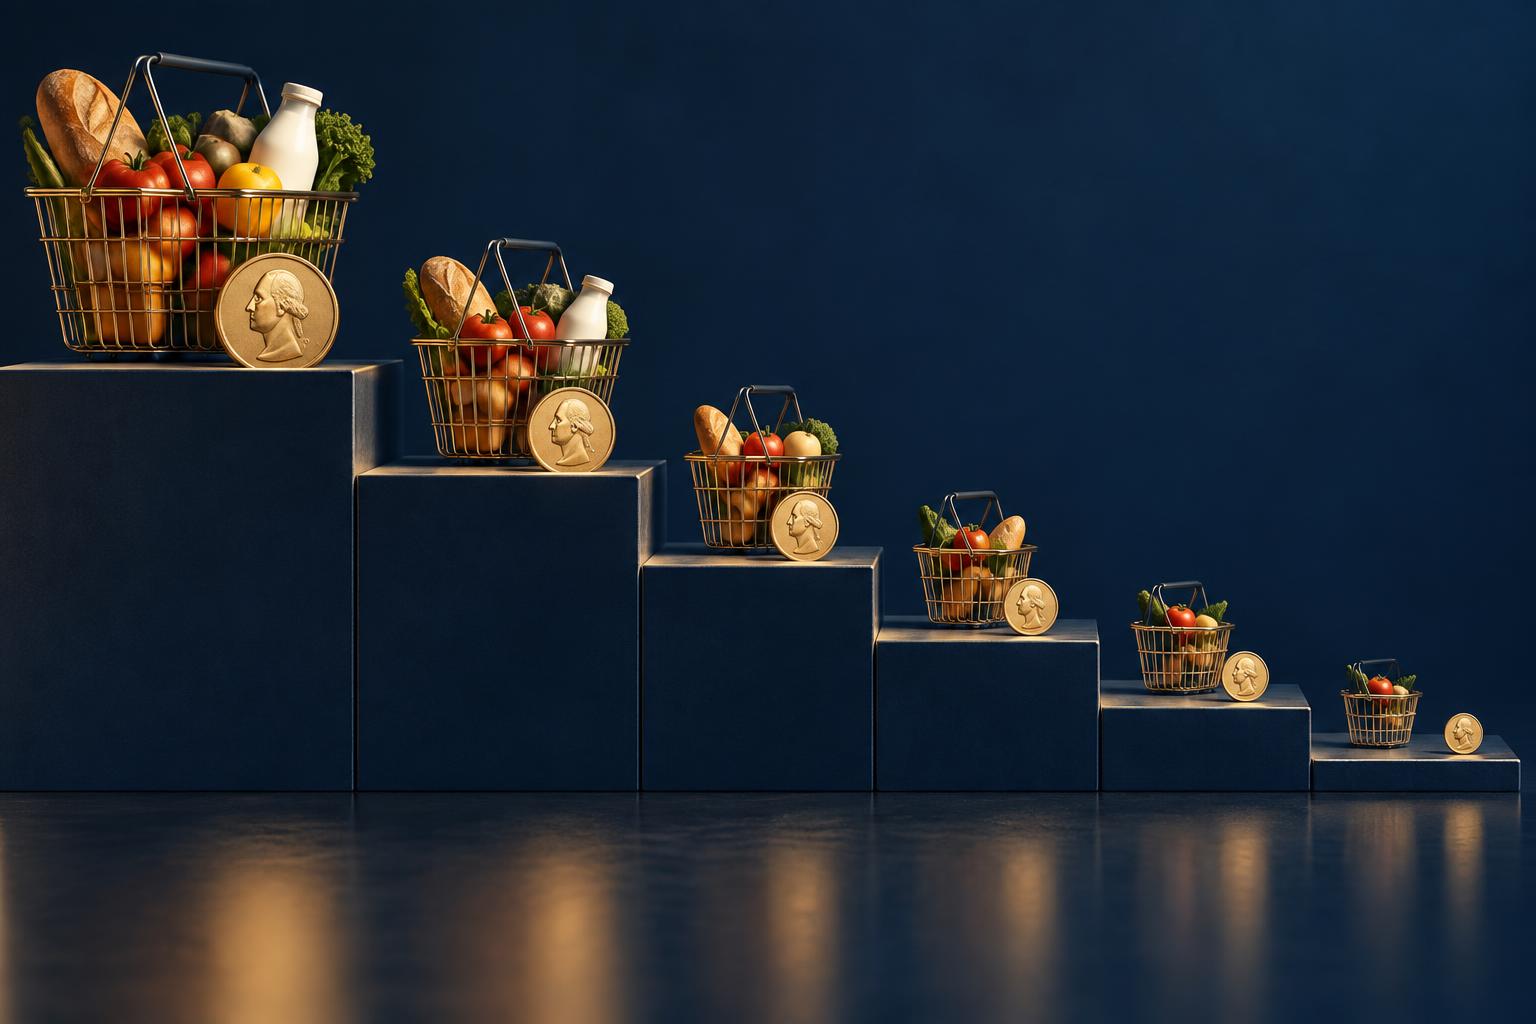
Chart showing the decline in what one U.S. dollar buys across recent decades
Purchasing power is measurable: the BLS Consumer Price Index series records how much less a dollar buys over time. What any asset does about it is not measurable in advance.
Describe this illustration: Chart showing the decline in what one U.S. dollar buys across recent decades

A descending line showing the real purchasing power of one dollar over successive decades, derived from the Consumer Price Index published by the U.S. Bureau of Labor Statistics. The measurement is well documented. Its limits belong with it: CPI is one basket, methodology has changed over time, and individual households experience different inflation. The chart says what a dollar bought — not what any investment will do next.
Reserve share is not reserve status

The IMF's COFER series reports the currency composition of allocated official reserves. It shows the dollar's share drifting lower across two decades, with the gains spread across several smaller currencies rather than concentrated in one challenger, and with the dollar still far larger than anything else.

That is diversification, and it is the accurate word. Reserve-currency status rests on depth of financial markets, legal predictability, the size of the government-securities market and network effects in trade and finance. A declining share within a still-dominant position is a real change and a modest one. Presenting it as imminent replacement is not supported by the series.

Diagram of central bank reserve asset composition and the share held as gold
Reserve managers hold a mix: foreign-currency securities, deposits, IMF positions and gold. Diversification within that mix is what the data actually shows.
Describe this illustration: Diagram of central bank reserve asset composition and the share held as gold

A composition diagram of official reserve assets, separating foreign-currency reserves from gold and IMF-related positions. The IMF's COFER series reports the currency split of allocated reserves; it shows the dollar's share drifting lower over two decades while remaining the largest by a wide margin. Reserve share and reserve status are different measurements, and the diagram is here to keep them apart.

Settlement plumbing, and why announcements mislead

Most reported de-dollarization events concern this layer: a bilateral local-currency agreement, a regional settlement platform, a memorandum between central banks. These are real, and they are growing from a small base.

The test is volume, not announcement. A summit communiqué is not evidence of a shift; measurable settlement flow is. When you read the next headline, ask three questions: which of the five layers does this concern, is there a published volume, and has anything changed for holders of dollar assets. Most of the time the honest answer to the third question is 'not yet, and not measurably'.

Diagram of cross-border payment rails and alternative settlement arrangements
Settlement plumbing is a separate question from reserve holdings. Alternative rails exist and are growing from a small base — that is the accurate statement.
Describe this illustration: Diagram of cross-border payment rails and alternative settlement arrangements

A schematic of cross-border payment routing: correspondent banking and dominant messaging arrangements alongside bilateral, regional and local-currency settlement alternatives. The diagram distinguishes the announcement of an arrangement from measurable volume through it. Most reported de-dollarization events are announcements about this layer, not changes in reserve composition.

Monetary arrangements are decisions, with dates

In August 1971 the United States ended the dollar's convertibility into gold at a fixed rate. Reserve currencies before the dollar — sterling, and others further back — held that position for long periods and then did not. This history is included for one reason: it establishes that monetary arrangements are policy choices rather than natural laws, which makes 'what would a change look like?' a reasonable question.

It establishes nothing about timing. Every previous transition took decades and was visible mostly in hindsight. Anyone naming a year is guessing, and should say so.

Explainer illustration of the 1971 end of dollar convertibility into gold
In 1971 the United States ended the dollar's convertibility into gold. Monetary arrangements are decisions, and decisions change — which is the honest version of the macro question.
Describe this illustration: Explainer illustration of the 1971 end of dollar convertibility into gold

The plate marks the closing of the gold window in August 1971, when foreign official holders lost the right to convert dollars into gold at a fixed rate. It is included as history rather than as prophecy: the point is that reserve and monetary arrangements are policy choices with start and end dates, so asking what a change would look like is a reasonable question rather than an alarmist one.

From the question to what a household can reasonably do

If the honest summary is 'gradual diversification, well measured in reserves and poorly measured in settlement, with no replacement in sight', then the reasonable response is not a dramatic one. It is the ordinary discipline of not having every asset exposed to the same single risk.

Physical precious metals are one of several assets that behave differently from currency-denominated ones, because they have no issuer. They are also volatile, produce no income, cost something to hold, and have gone long stretches without keeping pace with inflation. Both halves of that sentence are true, and any page that gives you only one half is selling you something. If you want to go deeper on the industrial and monetary evidence for silver specifically, that is the next page — not a purchase.

Portfolio diagram showing a modest precious-metals share balanced against other holdings
Metals are usually discussed as a share of a portfolio rather than a replacement for one. The right share depends on the household, not on a headline.
Describe this illustration: Portfolio diagram showing a modest precious-metals share balanced against other holdings

A balance diagram placing a precious-metals allocation next to other holdings. Published institutional discussion of metals allocation ranges widely and depends on objective, time horizon and income needs. Capstone Metals does not publish a single recommended percentage, because the number that fits a retired household with income needs is not the number that fits a saver two decades from retirement.

What remains unknown

Stated plainly, because a page about macroeconomics that admits nothing is not research.

  • Whether reserve diversification continues at the same pace, accelerates, or reverses.
  • Whether alternative settlement arrangements reach volumes that matter globally.
  • What inflation does next, and whether any particular asset responds to it as it has before.
  • Whether official gold buying continues, and what reserve managers will decide next.
  • How policy choices — fiscal, monetary and regulatory — change any of the above.

Questions people actually ask

What does de-dollarization actually mean?

It is shorthand for up to five distinct changes: reserve diversification away from dollar assets, trade invoiced and settled in other currencies, use of alternative payment systems, currency substitution by households and firms, and accumulation of gold by central banks. Most reporting concerns one layer and implies all five. Separating them is most of the analytical work.

Is the dollar losing reserve-currency status?

Not on the available evidence. IMF COFER data shows the dollar's share of allocated reserves drifting lower over two decades while remaining the largest by a wide margin, with gains spread across several smaller currencies. That is diversification within continued dominance. Status rests on market depth, legal predictability and network effects, none of which have changed materially.

Will BRICS launch a currency that replaces the dollar?

No such currency exists, and announcements of intent are not the same as a functioning reserve currency, which requires deep bond markets, convertibility and legal predictability. We do not treat summit statements as evidence, and we do not publish dated predictions about this.

Does gold or silver protect against dollar devaluation?

Sometimes, over long horizons, and unreliably over short ones. Gold and silver have gone multi-year stretches without keeping pace with measured inflation, including after previous peaks. They have no issuer, which is a genuine structural difference from currency-denominated assets, but that is not a guarantee of purchasing-power protection and we will not describe it as one.

What would actually signal a meaningful shift?

Sustained declines in the dollar's COFER share beyond the existing trend; published settlement volumes — not agreements — moving materially into other currencies; a deep, convertible alternative government-bond market; and reserve managers stating changed policy. Those are measurable. Watch them instead of headlines.

Is this a political argument?

No. Reserve composition, settlement volumes and price indices are measured by institutions with published methodologies, and they behave the same regardless of which party holds office. We keep this page monetary, and we label opinion as opinion where we offer any.

Read further on our research pages

Later in the journey, not now

Retirement-account mechanics belong after the macro question is understood, and only if a retirement account is involved at all.

Retirement-account mechanics

Sources

Read the evidence, at your own pace

The guide collects the reserve, settlement and purchasing-power data with sources named and dated, and includes the arguments against the diversification thesis. There is no purchase involved and no obligation to speak to anyone.

Disclosures

Who you are dealing with. Capstone Metals is a DBA (“doing business as”) name of TB Alternative Assets LLC, a California-registered company. TB Alternative Assets LLC is the legal entity that owns and operates Capstone Metals and is the contracting party on every order, agreement and disclosure on this site. Our office: 5311 Topanga Canyon Blvd, Woodland Hills, CA, 91364. Telephone (800) 200-9553, info@capstonemetals.com. Monday – Friday, 7am – 4pm Pacific.

Market risk. Capstone Metals does not promise or project the future price of any metal. Precious metals are speculative, produce no income, and can be sold for less than you paid. Past performance never guarantees future results, and nothing on this page is a forecast, projection or assurance of any outcome.

Costs. Every physical metals transaction includes a premium over the spot price, and dealer buy and sell prices include a spread. Retirement accounts additionally carry custodian setup, annual administration and depository storage fees set by those independent firms. All applicable amounts are disclosed to you in writing before you commit to anything.

Not advice. This page is education, not investment, tax or legal advice, and it is not an offer or a recommendation. Custodians and depositories are independent third parties, not affiliates of Capstone Metals. Discuss your situation with your own tax professional, attorney and any advisor you trust before acting.

By submitting your name and phone number you are asking us to follow up, and you agree that Capstone Metals may contact you by phone, text, or email to clarify what you are looking for and make sure you receive it. Message and data rates may apply. You can ask us to stop at any time by replying STOP or telling us on the phone, and we never sell or share your information. This is a request for information and a conversation — not a purchase, an application, or advice.

Read the full risk disclosures, disclaimer and privacy policy.

Call (800) 200-9553 Text Email