Capstone Metals — gold and silver IRA dealer
Speak with a specialist: (800) 200-9553Monday – Friday, 7am – 4pm Pacific

Official sector

Why central banks hold gold — the reasons they actually publish

This page is about rationale, not headlines: not how much gold central banks bought last quarter, but why the asset is in a reserve portfolio at all. The reasons are written down, in central-bank publications, IMF notes and market-body references, and they are less dramatic and more instructive than the versions circulated online.

Monday – Friday, 7am – 4pm Pacific

  • Licensed and insured since 2014
  • Fiduciary advisory — licensed since 1970
  • Preferred Trust & GoldStar custodians
  • No card payments, no pressure, no commissions-first pitch

Credit risk

None — no issuer

Purpose

Reserve diversification

IMF caveat

Volatile; benefits conditional

Household parallel

Limited — different job

The five reasons that recur

EXPERT ANALYSIS. Across official and institutional publications the same considerations appear. First, no credit risk: gold is not another government's or bank's obligation, so it cannot be defaulted on or frozen by an issuer. Second, diversification: a reserve portfolio otherwise concentrated in a few currencies and their sovereign bonds gains an asset that behaves differently. Third, market depth and liquidity: gold can be transacted in size through an established market. Fourth, crisis utility: it has proved usable when other assets or channels were impaired. Fifth, historical and strategic considerations particular to each country, including holdings inherited from earlier monetary regimes.

  • No credit risk — no issuer that can default
  • Diversification away from currency and sovereign-bond concentration
  • Depth and liquidity in an established global market
  • Demonstrated usefulness in crises
  • Country-specific history and strategy
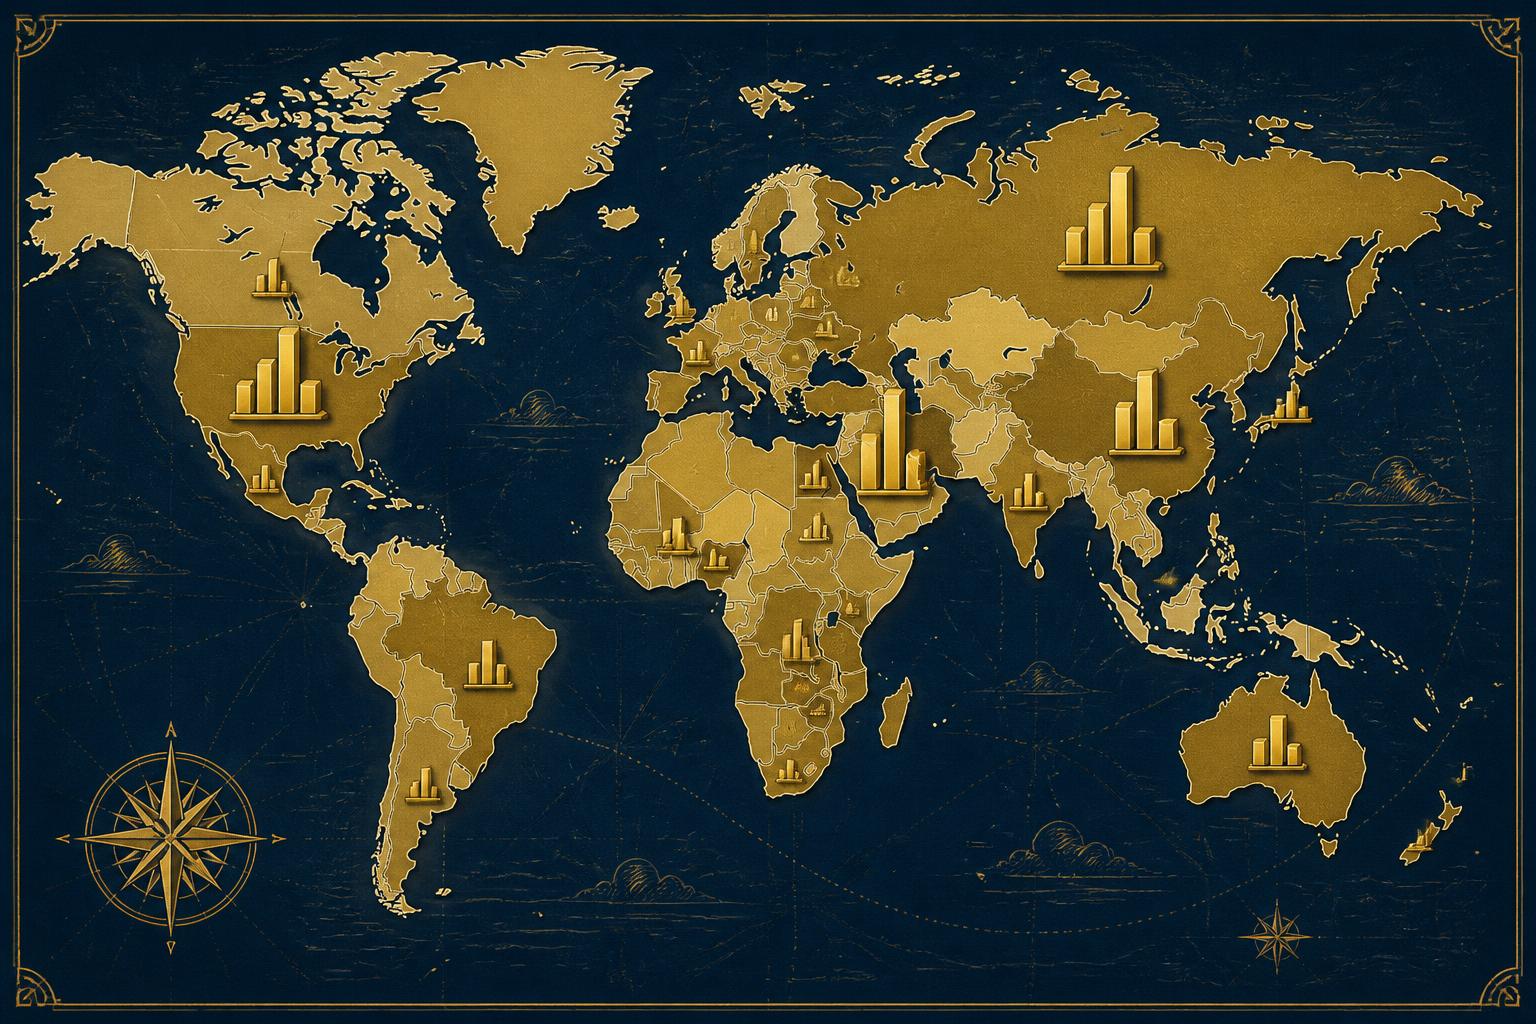
Stylised gold-toned world map on navy with countries shaded at different intensities and small gold bar icons of varying size placed over several regions
Who holds official gold is public information. Governments and central banks report their reserves, and the reported holdings are substantial and widely distributed.
Describe this illustration: Stylised gold-toned world map on navy with countries shaded at different intensities and small gold bar icons of varying size placed over several regions

An original Capstone Metals illustration of a point that needs no conspiracy to make: official gold holdings are disclosed, not hidden. Reserve institutions publish their gold positions, international bodies compile them, and anyone can read them. The map is a schematic of that public picture — deliberately unlabelled, because reported holdings change and the source data should be read directly rather than trusted from an illustration. What it does not show, because public evidence does not establish it, is any secret accumulation by anyone.

The IMF's caveats, stated as prominently as the case

EXPERT ANALYSIS. The IMF's July 2026 note for reserve managers is the most useful document on this subject precisely because it does not advocate. It records that gold features prominently in reserves and carries no credit risk — and it states that gold is volatile and that its hedging, safe-haven and diversification benefits are conditional rather than automatic, with practical guidance on the market risks involved. If a page tells you central banks buy gold and stops there, it has left out the half of the official analysis that is inconvenient.

What reserve managers say about their own intentions

SURVEY EVIDENCE. The World Gold Council's 2026 survey of central-bank reserve managers reports that 93% of respondents held gold and 45% expected to increase holdings over the following twelve months. That is a survey — self-reported intent from responding institutions, gathered by the gold industry's trade body — and it should be cited as attitudes, not as a measurement of future flows. INDUSTRY ANALYSIS. LBMA material and a published Banque de France account describe how individual institutions think about and manage the holdings in practice.

Why a household is not a central bank

The gap matters and is rarely stated. A central bank owns its vault, has no personal expenses, need never sell at a bad moment, and holds gold to make a national balance sheet resilient across decades and political cycles. A household pays a premium to buy, a spread to sell, and a fee to store, and may need the money for a roof or a medical bill. So the official-sector case supports one modest conclusion for private savers — that an asset without an issuer plays a distinct role — and supports no conclusion at all about how much of it anyone should own.

What this does NOT prove

It does not prove that gold will appreciate, that official buying will continue, or that central banks expect a currency crisis. Reserve managers are managing a portfolio, not signalling a forecast, and the IMF's own note is explicit that the benefits depend on conditions. And none of the institutions cited here has any view on Capstone Metals, gold IRAs or any dealer.

Rather just ask someone?

A specialist can answer this in two minutes. Monday – Friday, 7am – 4pm Pacific.

Would a short, no-pressure conversation help?

Leave your name and number. A Capstone specialist will answer your questions during business hours.

Most gold and silver firms can only talk to you about gold and silver. We have licensed advisors on staff, so the same conversation can cover your retirement accounts, your market holdings, insurance and estate structure alongside a completely private metals purchase — one fiduciary review of everything you own, not a sales call about one product.

What would you like help understanding? (optional)

By submitting your name and phone number you are asking us to follow up, and you agree that Capstone Metals may contact you by phone, text, or email to clarify what you are looking for and make sure you receive it. Message and data rates may apply. You can ask us to stop at any time by replying STOP or telling us on the phone, and we never sell or share your information. This is a request for information and a conversation — not a purchase, an application, or advice. SMS Opt-In Policy · Privacy Policy · Terms & Conditions · How pricing works · Disclosures · Due diligence & financial risks

Licensed and insuredFiduciary advisory since 1970Independent IRA custodiansPrices quoted, never card-charged

Want a number rather than a conversation first? Request current gold pricing — itemized spot reference and premium, with the research and its limits sent afterwards.

Common questions

Why do central banks buy gold?
For diversification, because it carries no credit risk, because the market is deep enough to transact in size, because it has been useful in crises, and for country-specific strategic and historical reasons. Those are the reasons in their own publications.
Does the IMF recommend gold?
No. Its 2026 note is guidance for reserve managers: gold is prominent in reserves and free of credit risk, and it is volatile with conditional hedging and diversification benefits. That is an assessment, not a recommendation, and it says nothing about private investors.
Is 93% of central banks holding gold a fact?
It is a survey result — 93% of responding reserve managers reported holding gold in the World Gold Council's 2026 survey, with 45% expecting to add over the next year. Self-reported answers collected by an industry body, so read it as reported attitudes.
Should I copy what central banks do?
No, not directly. Their horizon, costs and purpose differ from yours in every respect. The useful takeaway is why an asset with no issuer earns a place in a portfolio, not what percentage a nation holds.
How allocation is actually decided

Talk with a Capstone specialist about your situation

Reserve-management reasoning is interesting; your own balance sheet is the thing that matters. Leave a name and number and a specialist — or a licensed advisor where the question spans retirement accounts, market holdings or insurance — will walk through it with you. No obligation.

Licensed and insuredFiduciary advisory since 1970Independent IRA custodiansPrices quoted, never card-charged
Call (800) 200-9553 Text Email