


Capstone Metals — gold and silver IRA dealer
Speak with a specialist: (800) 200-9553Monday – Friday, 7am – 4pm Pacific

Rollover

Can I move my 403(b) into gold?

Teachers, hospital staff and nonprofit employees ask this for a specific reason: a 403(b) is often the only retirement account they have, it is frequently sitting inside an insurance annuity nobody explained to them, and the fees are hard to find. This page answers whether the money can move, what it will cost to move it, and the one charge that catches people out — before anyone asks you to sign anything.

Monday – Friday, 7am – 4pm Pacific

  • Licensed and insured since 2014
  • Fiduciary advisory — licensed since 1970
  • Preferred Trust & GoldStar custodians
  • No card payments, no pressure, no commissions-first pitch

Former employer plan

Almost always eligible

Still employed

Usually restricted before 59½

Annuity contracts

Check the surrender schedule

Direct rollover tax

None

The honest answer to “is my 403(b) any good?”

FACT. Many 403(b) plans, particularly in K–12 districts, are sold through insurance agents and held in annuity contracts whose costs are layered — a contract charge, a mortality and expense charge, and the underlying fund expense. Others hold ordinary mutual funds in a custodial account and are inexpensive. Yours could be either, and the plan document tells you which. UNKNOWN: nobody can tell you your costs without seeing your statement, and any firm that names a figure before reading it is guessing.

  • Annuity-based 403(b): layered charges, and often a surrender schedule
  • Custodial (mutual fund) 403(b): usually simpler and cheaper
  • The plan document and your statement settle it in ten minutes
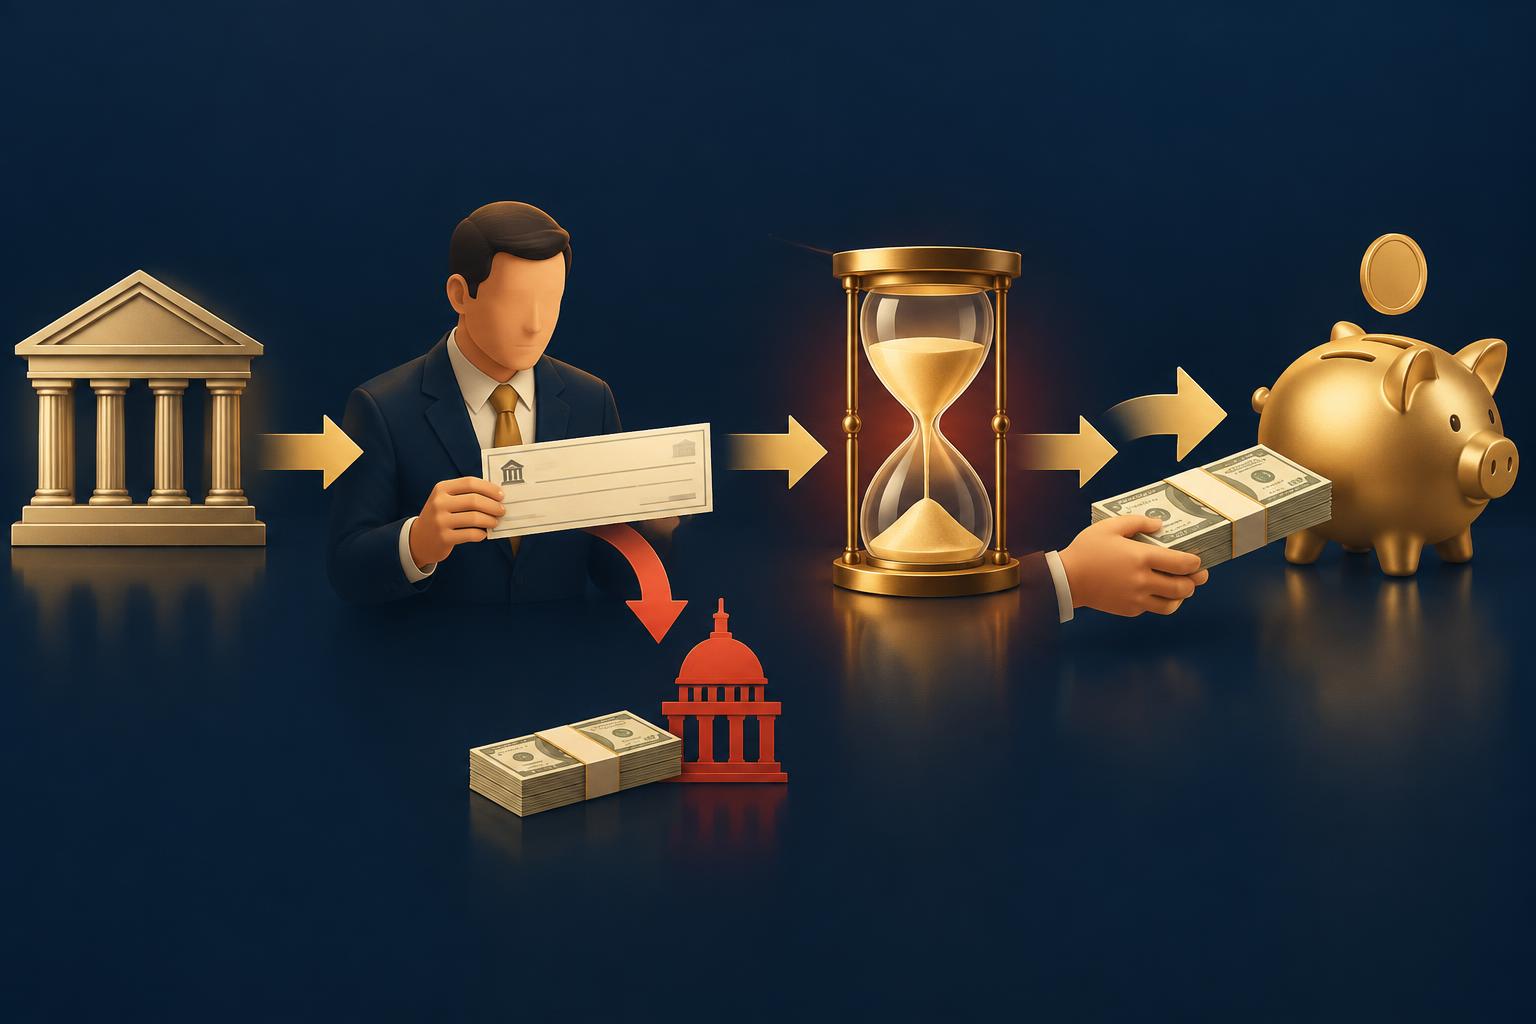
Timeline diagram of an indirect rollover showing tax withheld at the start and a sixty day deadline to redeposit the full amount
The route that creates the penalty people fear — and the one a direct rollover avoids entirely.
Describe this illustration: Timeline diagram of an indirect rollover showing tax withheld at the start and a sixty day deadline to redeposit the full amount

The route that creates the penalty people fear — and the one a direct rollover avoids entirely. This original Capstone Metals diagram illustrates timeline diagram of an indirect rollover showing tax withheld at the start and a sixty day deadline to redeposit the full amount. It is educational artwork, not a price forecast, performance record or recommendation.
When the money is allowed to move

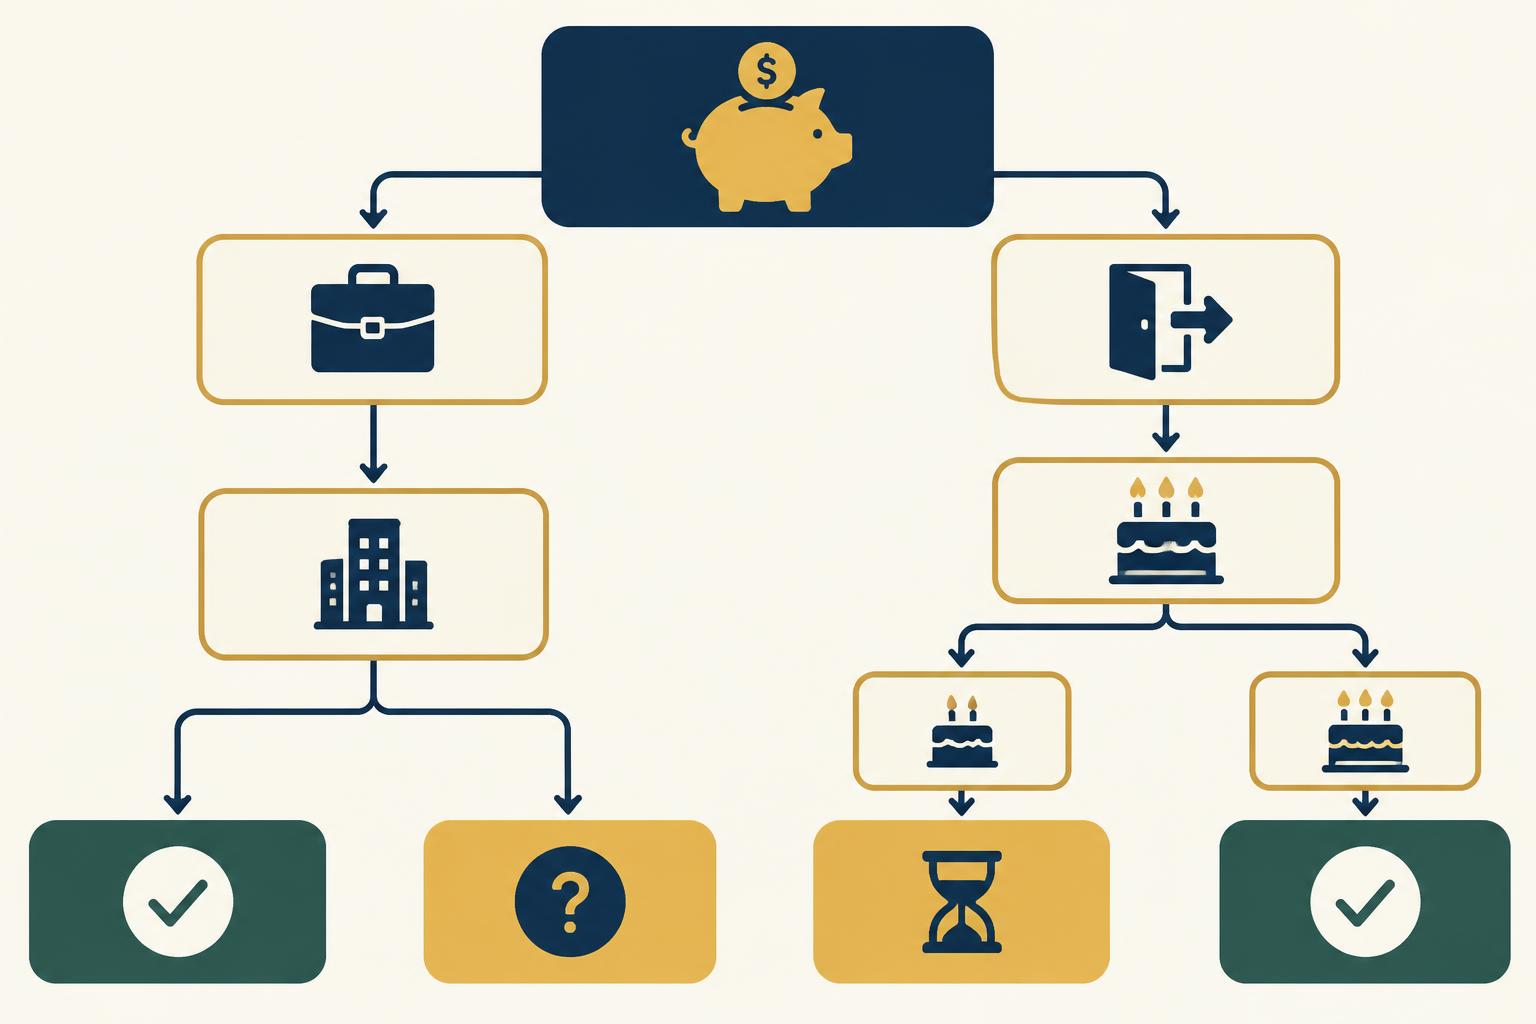
FACT. The clean path is separation from service — leaving or retiring from the employer sponsoring the plan. Most 403(b) plans do not permit in-service rollovers before 59½; many allow them after. A 403(b) left behind at a former district, hospital or charity is almost always fully eligible today, and those are the accounts people most often forget they own.

  • Separated or retired: eligible, in full
  • Still employed and 59½ or older: often eligible — ask specifically
  • Still employed and younger: usually not, but an old plan elsewhere may be
Decision tree branching on former or current employer and age, ending in eligible, partially eligible or wait
Two questions to your plan administrator settle eligibility. Here they are in order.
Describe this illustration: Decision tree branching on former or current employer and age, ending in eligible, partially eligible or wait

Two questions to your plan administrator settle eligibility. Here they are in order. This original Capstone Metals diagram illustrates decision tree branching on former or current employer and age, ending in eligible, partially eligible or wait. It is educational artwork, not a price forecast, performance record or recommendation.

The surrender charge that catches people

FACT. If your 403(b) is an annuity, exiting early can trigger a surrender charge — commonly a percentage that steps down over several contract years. It is a real cost and it is avoidable: ask your provider for the surrender schedule in writing before starting anything. Sometimes waiting for one contract anniversary saves more than the entire first year of a metals account costs. We will read the schedule with you rather than rushing past it.

Doing it without tax or penalty

FACT. A direct trustee-to-trustee rollover is not a distribution, so there is no income tax and no early-withdrawal penalty at any age. Pre-tax balances go to a traditional IRA; Roth 403(b) balances go to a Roth IRA with their tax-free treatment intact. If instead the plan pays you personally, withholding applies and a 60-day clock starts — that is the route that creates the penalty people fear.

  • Open the self-directed IRA first, so a receiving account exists
  • Request the rollover in writing, naming the new custodian as payee
  • Select IRS-eligible bullion once funds settle; the depository stores it

What it costs, stated plainly

There is a custodian account fee, an annual depository storage fee, and a premium over the spot price on the metal itself. Capstone works with Preferred Trust Company and GoldStar Trust Company — independent custodians that hold the account, not us. Every figure is quoted in writing before you commit, and no card is charged at any point.

Whether you should, not just whether you can

Public-sector and nonprofit workers often have a pension alongside the 403(b), which changes the picture entirely — a guaranteed income stream is itself a form of ballast. Because Capstone has licensed financial advisors on staff, the conversation can weigh the pension, the 403(b), any spouse's plan and your income needs together. If the sensible answer is to leave it alone, we would rather say so.

Reaching us

Capstone Metals is operated by TB Alternative Assets LLC, a California-registered company, working with families across the United States by phone and text: (800) 200-9553, Monday to Friday, 7am to 4pm Pacific. Bring your statement to the call and we will go through it line by line — including the parts that argue against moving.

Rather just ask someone?

A specialist can answer this in two minutes. Monday – Friday, 7am – 4pm Pacific.

Would a short, no-pressure conversation help?

Leave your name and number. A Capstone specialist will answer your questions during business hours.

Most gold and silver firms can only talk to you about gold and silver. We have licensed advisors on staff, so the same conversation can cover your retirement accounts, your market holdings, insurance and estate structure alongside a completely private metals purchase — one fiduciary review of everything you own, not a sales call about one product.

What would you like help understanding? (optional)

By submitting your name and phone number you are asking us to follow up, and you agree that Capstone Metals may contact you by phone, text, or email to clarify what you are looking for and make sure you receive it. Message and data rates may apply. You can ask us to stop at any time by replying STOP or telling us on the phone, and we never sell or share your information. This is a request for information and a conversation — not a purchase, an application, or advice. SMS Opt-In Policy · Privacy Policy · Terms & Conditions · How pricing works · Disclosures · Due diligence & financial risks

Licensed and insuredFiduciary advisory since 1970Independent IRA custodiansPrices quoted, never card-charged

Want a number rather than a conversation first? Request current gold pricing — itemized spot reference and premium, with the research and its limits sent afterwards.

Common questions

Can I move my 403(b) to gold?
Yes, indirectly — a 403(b) cannot hold bullion itself, so the money rolls into a self-directed IRA that can. Done as a direct trustee-to-trustee rollover there is no tax and no penalty.
How to move retirement money without a penalty
Can I roll over my 403(b) while still teaching?
Usually not before age 59½, because most plans restrict in-service distributions. After 59½ many plans allow it. A 403(b) from a former district or employer is almost always eligible now.
Will a 403(b) rollover to a gold IRA be taxed?
Not when it is a direct rollover between custodians. Traditional balances stay traditional, Roth stays Roth. Tax and the 10% additional tax under 59½ only appear if the money is paid to you and not redeposited within 60 days.
Direct versus indirect rollovers
What about surrender charges on my 403(b) annuity?
Ask your provider for the surrender schedule in writing before you start. Charges typically decline over contract years, so timing can save real money. This is the single most common avoidable cost in a 403(b) rollover.
I have a pension as well — does that change anything?
It changes a great deal. A pension is a guaranteed income stream, which is itself a stabiliser, and households with one often need less defensive allocation elsewhere. That is a conversation for a licensed advisor looking at the whole picture, not a metals decision in isolation.
A review of everything you own
How much of my 403(b) should go into metals?
Common frameworks treat physical metals as a minority ballast — often 5% to 20% — rather than a whole account, and most people who do this move only a portion. The right figure depends on your income needs and other holdings, so we will not name one for you sight unseen.
How much metal belongs in a portfolio
How long does it take?
Two to four weeks in most cases, driven mainly by how quickly the releasing provider acts. We cannot promise a date and will not pretend to.

Educators and nonprofit staff deserve straight answers

Leave your name and a phone number. We will confirm your plan's distribution rules with you on the line, read your surrender schedule if there is one, and tell you what it would cost — before any paperwork starts.

Licensed and insuredFiduciary advisory since 1970Independent IRA custodiansPrices quoted, never card-charged
Call (800) 200-9553 Text Email