


What you would be giving up — first, because it matters
FACT. The TSP's expense ratios are among the lowest available anywhere, and the G Fund is a security no private plan can replicate: principal that does not fall, at intermediate Treasury rates. FACT. The TSP also allows penalty-free withdrawals if you separate during or after the year you turn 55 (age 50, or after 25 years of service, for public-safety and certain uniformed roles), which is earlier than the IRA's 59½. Moving everything out forfeits both. Most federal retirees who add metals move a portion and keep the TSP open.
- G Fund: no private equivalent — principal stability at Treasury rates
- Expense ratios materially lower than most IRAs
- Earlier penalty-free access after separation at 55, or 50 in certain roles
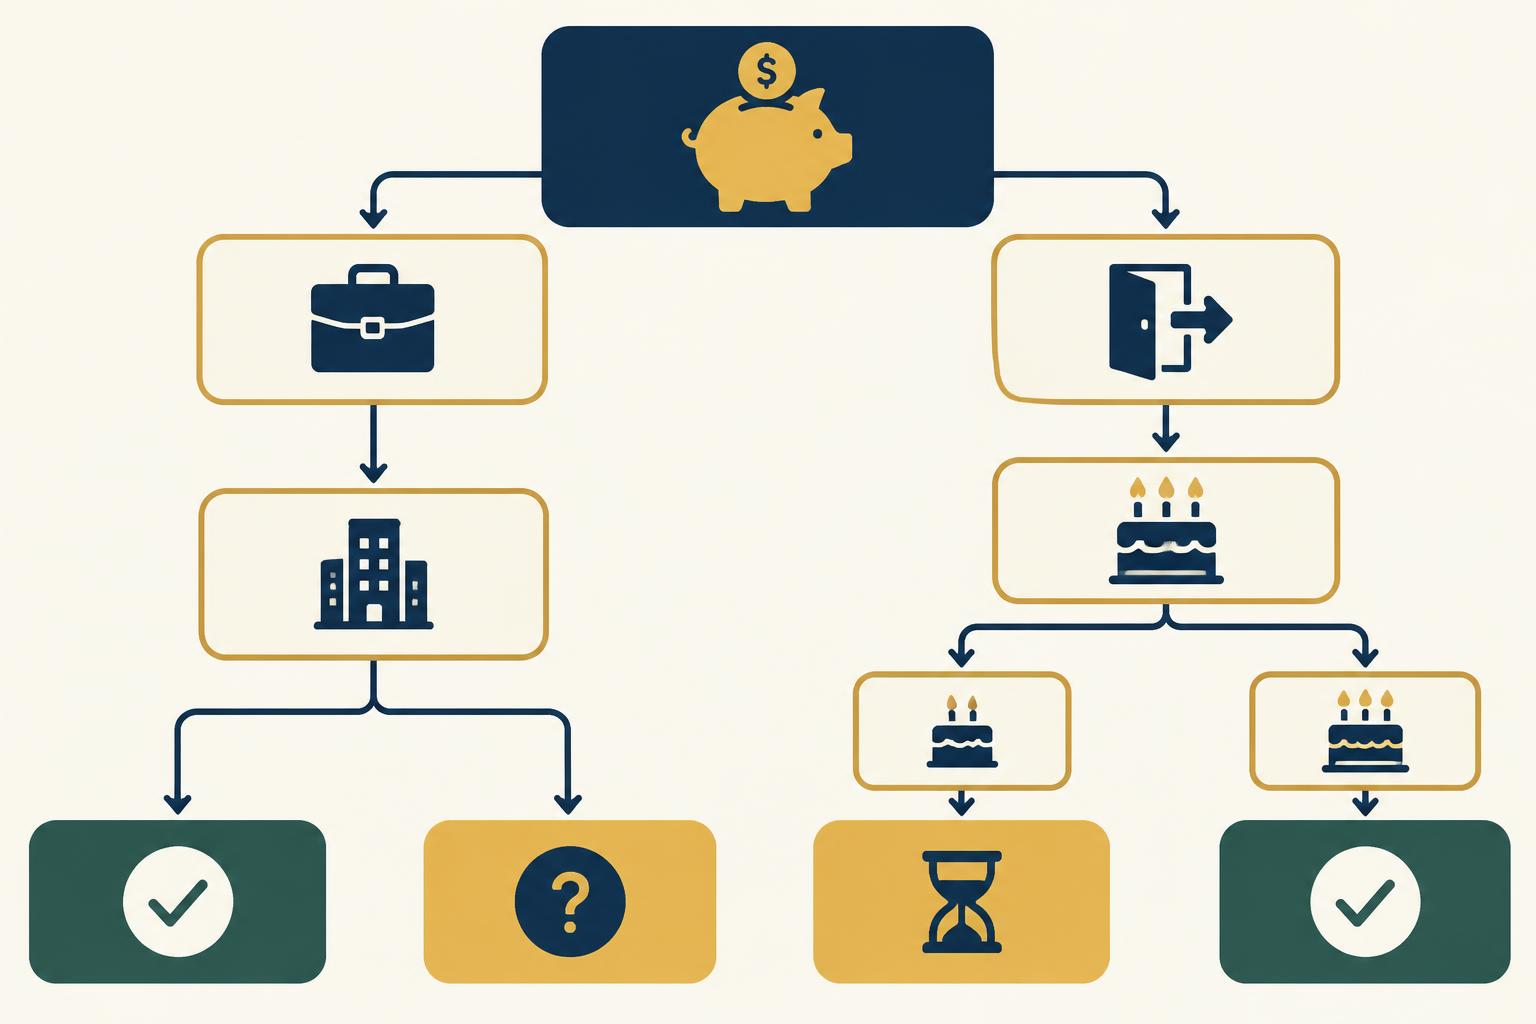
Describe this illustration: Decision tree branching on former or current employer and age, ending in eligible, partially eligible or waitHide description: Decision tree branching on former or current employer and age, ending in eligible, partially eligible or wait
Two questions to your plan administrator settle eligibility. Here they are in order. This original Capstone Metals diagram illustrates decision tree branching on former or current employer and age, ending in eligible, partially eligible or wait. It is educational artwork, not a price forecast, performance record or recommendation.