


Capstone Metals — gold and silver IRA dealer
Speak with a specialist: (800) 200-9553Monday – Friday, 7am – 4pm Pacific

Rollover

How to move a 401(k) to gold without a penalty

The fear behind this search is specific and reasonable: that moving retirement money into metal counts as cashing out, and that the IRS takes a bite. Done one particular way it does not — no tax, no penalty, nothing reported as income. Done a different way it can cost you 20% of the transfer up front and a 10% penalty on top. The difference is the paperwork, and it is worth understanding before you start.

Monday – Friday, 7am – 4pm Pacific

  • Licensed and insured since 2014
  • Fiduciary advisory — licensed since 1970
  • Preferred Trust & GoldStar custodians
  • No card payments, no pressure, no commissions-first pitch

Direct rollover

No tax, no penalty

Indirect rollover

20% withheld, 60-day clock

Early-distribution penalty

10% if it becomes a withdrawal

Rollovers per year

Unlimited if trustee-to-trustee

Why a rollover is not a withdrawal

FACT. The Internal Revenue Code treats a qualifying rollover as a continuation of a tax-deferred account, not a distribution. Money leaves one custodian and arrives at another still inside the retirement system, so there is no taxable event and no early-distribution penalty regardless of your age. What triggers tax and penalty is a distribution — money reaching you personally and not going back in. The entire skill here is keeping the transaction on the first side of that line.
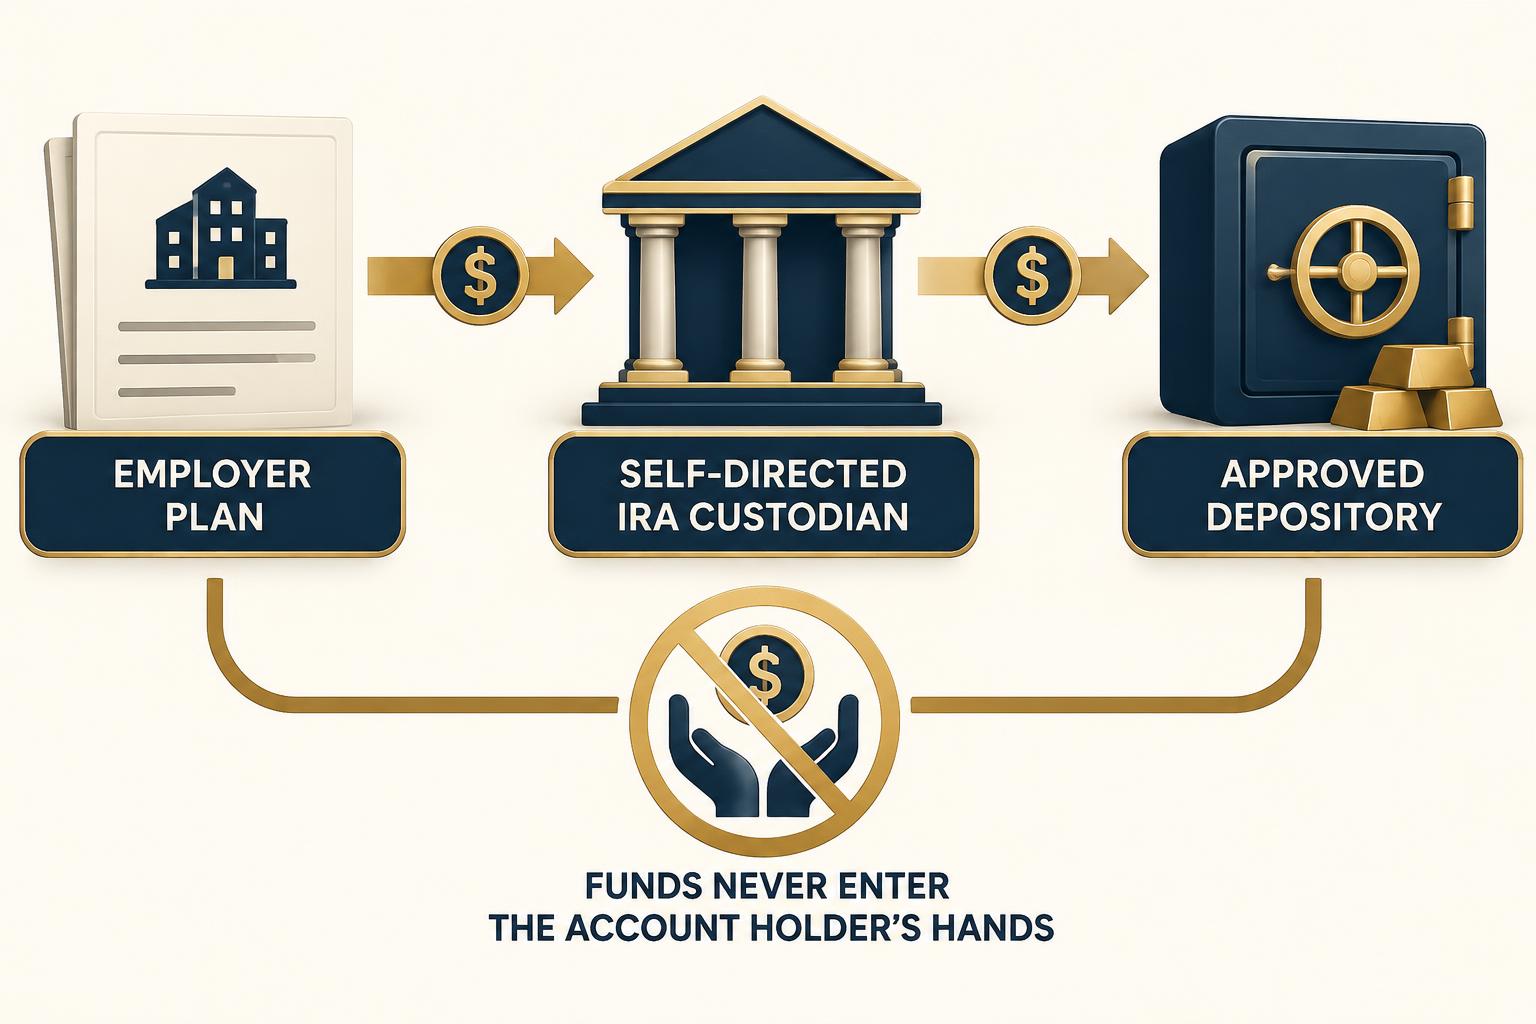
Numbered flow diagram from plan administrator to self-directed IRA custodian to depository, with the funds never passing through the account holder
A direct rollover moves funds custodian to custodian. That is what keeps it out of tax.
Describe this illustration: Numbered flow diagram from plan administrator to self-directed IRA custodian to depository, with the funds never passing through the account holder

A direct rollover moves funds custodian to custodian. That is what keeps it out of tax. This original Capstone Metals diagram illustrates numbered flow diagram from plan administrator to self-directed ira custodian to depository, with the funds never passing through the account holder. It is educational artwork, not a price forecast, performance record or recommendation.
Do it the direct way and there is almost nothing to get wrong

In a direct, trustee-to-trustee rollover the funds never touch your hands. Your plan administrator sends them straight to the new self-directed IRA custodian, and the custodian buys the metals you have chosen. There is no withholding, no 60-day deadline, no annual limit on how many you do, and nothing to report as income.

  • Open the self-directed IRA first, so the receiving account exists
  • Request a direct rollover from your plan — in writing, naming the new custodian
  • The plan sends funds custodian-to-custodian, never to you
  • You select IRS-eligible bullion; the custodian settles and the depository stores it
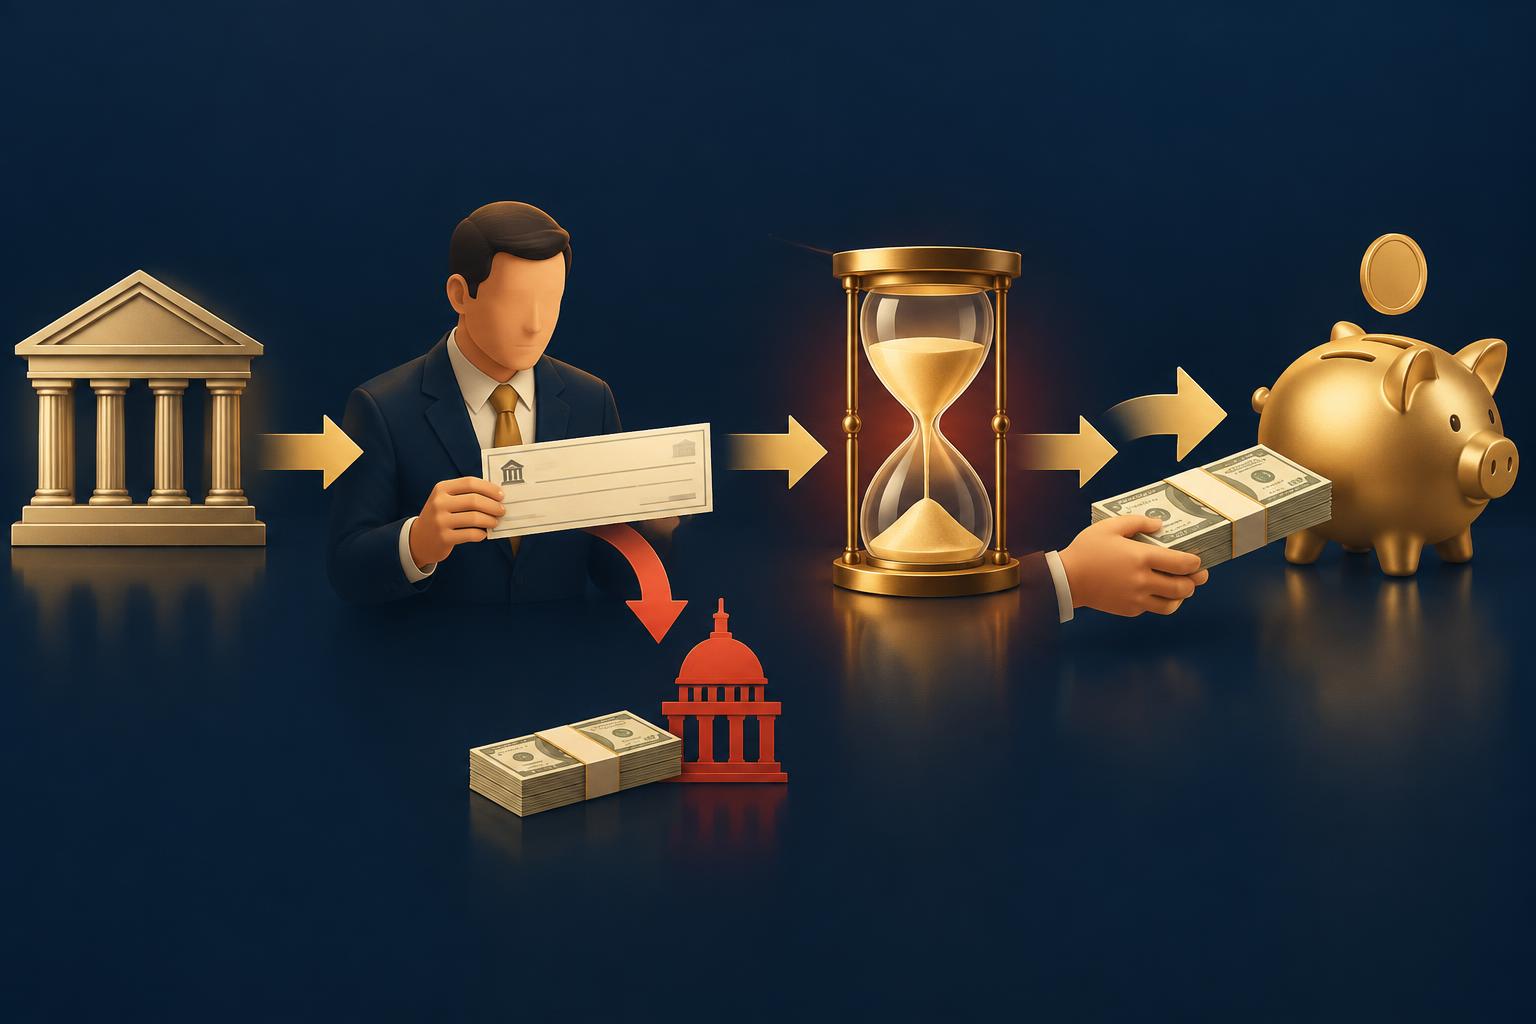
Timeline diagram of an indirect rollover showing tax withheld at the start and a sixty day deadline to redeposit the full amount
The route that creates the penalty people fear — and the one a direct rollover avoids entirely.
Describe this illustration: Timeline diagram of an indirect rollover showing tax withheld at the start and a sixty day deadline to redeposit the full amount

The route that creates the penalty people fear — and the one a direct rollover avoids entirely. This original Capstone Metals diagram illustrates timeline diagram of an indirect rollover showing tax withheld at the start and a sixty day deadline to redeposit the full amount. It is educational artwork, not a price forecast, performance record or recommendation.

The two mistakes that create the penalty people fear

FACT. First: taking an indirect rollover, where the plan writes you a check. A 401(k) must withhold 20% for federal tax on that payment, and to stay whole you must redeposit the full pre-withholding amount within 60 days — covering the withheld 20% out of pocket until you recover it at filing. Miss the 60 days and the shortfall becomes a taxable distribution, with a 10% additional tax if you are under 59½. Second: buying metal personally and trying to place it into the IRA afterwards. The IRS does not permit that, and home storage of IRA metal is not allowed.

  • Indirect rollover: 20% withheld, 60 days, out-of-pocket to stay whole
  • Missing the deadline turns the gap into income, plus 10% if under 59½
  • You cannot contribute metal you already own, and cannot store IRA metal at home

Whether your plan will let you move it at all

A plan from a former employer is almost always eligible for a full rollover. A current-employer plan depends on whether it permits in-service distributions — many do from age 59½, some earlier, some not at all. One call to your plan administrator settles it, and there are exactly two questions to ask: is a direct rollover to an IRA available, and does the plan allow in-service distributions? We will tell you what to say.

  • Former employer 401(k), 403(b), 457(b) or TSP: usually fully eligible
  • Current employer: ask specifically about in-service distributions
  • Partial rollovers are commonly allowed — you need not move everything

What the metal side actually requires

FACT. IRA metals must meet IRS fineness standards, be held by an approved custodian, and be stored at an approved depository — Capstone works with Preferred Trust Company and GoldStar Trust Company, which are independent of us and hold the account, not Capstone. There are custodian and storage fees, and the price you pay for bullion includes a premium over spot. None of that is hidden here, because a rollover that surprises you later is a bad rollover.

  • Eligible bullion only, at the required fineness
  • An independent custodian holds the account, not Capstone
  • Custodian, storage and premium costs are real and quoted before you commit

And the question underneath the question

Most people asking how to do this are really asking whether they should. That deserves an answer too, and it is not automatically yes. Because Capstone has licensed financial advisors on staff, the same conversation can look at your whole position — the plan, other holdings, income needs, insurance and estate structure — rather than metals in isolation. If a rollover is not right for you, we would rather say so than complete one.

Rather just ask someone?

A specialist can answer this in two minutes. Monday – Friday, 7am – 4pm Pacific.

Would a short, no-pressure conversation help?

Leave your name and number. A Capstone specialist will answer your questions during business hours.

Most gold and silver firms can only talk to you about gold and silver. We have licensed advisors on staff, so the same conversation can cover your retirement accounts, your market holdings, insurance and estate structure alongside a completely private metals purchase — one fiduciary review of everything you own, not a sales call about one product.

What would you like help understanding? (optional)

By submitting your name and phone number you are asking us to follow up, and you agree that Capstone Metals may contact you by phone, text, or email to clarify what you are looking for and make sure you receive it. Message and data rates may apply. You can ask us to stop at any time by replying STOP or telling us on the phone, and we never sell or share your information. This is a request for information and a conversation — not a purchase, an application, or advice. SMS Opt-In Policy · Privacy Policy · Terms & Conditions · How pricing works · Disclosures · Due diligence & financial risks

Licensed and insuredFiduciary advisory since 1970Independent IRA custodiansPrices quoted, never card-charged

Want a number rather than a conversation first? Request current gold pricing — itemized spot reference and premium, with the research and its limits sent afterwards.

Common questions

How do I move a 401(k) to gold without a penalty?
Use a direct, trustee-to-trustee rollover into a self-directed IRA that permits precious metals. Because the funds move custodian-to-custodian and never reach you personally, there is no distribution, so no income tax and no early-withdrawal penalty at any age.
Can I transfer my 401(k) to gold without penalty while still working?
Only if your plan allows in-service distributions. Many permit them from age 59½. If yours does not, you can usually still move an older plan from a former employer, and start the current one when you separate.
401(k) to Gold IRA eligibility
What is the 60-day rollover rule?
If a plan pays retirement funds to you rather than to another custodian, you have 60 days to deposit them into the receiving retirement account. Because a 401(k) must also withhold 20% for tax, you would need to make up that 20% from other money to redeposit the full amount. Missing the window makes the shortfall taxable, plus 10% if you are under 59½. A direct rollover avoids all of it.
Is there a limit on how many rollovers I can do?
The once-per-12-month limit applies to indirect IRA-to-IRA rollovers. Direct trustee-to-trustee transfers are not subject to that limit, which is another reason the direct route is the standard advice.
Can I keep the gold at home?
Not for IRA metal. IRS rules require an approved custodian and an approved depository; taking personal possession of IRA metal can be treated as a distribution. If holding metal yourself is what you want, that is a private cash purchase outside the IRA — a legitimate choice, just a different one.
How storage and depositories work
Do I have to move the whole 401(k)?
Usually no. Most plans allow partial rollovers, so you can allocate a portion to metals and leave the rest invested where it is.
How long does it take?
Most direct rollovers settle within one to three weeks, driven almost entirely by how quickly the releasing plan acts. We cannot promise a date, and we will not pretend to.

Get the exact steps for your plan

Leave your name and a phone number. We will tell you whether your plan qualifies, what to ask your administrator, and what it would cost — before you commit to anything.

Licensed and insuredFiduciary advisory since 1970Independent IRA custodiansPrices quoted, never card-charged
Call (800) 200-9553 Text Email