


Capstone Metals — gold and silver IRA dealer
Speak with a specialist: (800) 200-9553Monday – Friday, 7am – 4pm Pacific

Portfolio research

Gold vs stocks and bonds: what each asset is actually for

The usual version of this comparison is a chart of past returns, which answers the wrong question. Returns tell you what happened; structure tells you what each asset is for and how it fails. A portfolio built on structure survives conditions the chart never showed — and that, not performance, is the entire argument for holding assets that behave differently.

Monday – Friday, 7am – 4pm Pacific

  • Licensed and insured since 2014
  • Fiduciary advisory — licensed since 1970
  • Preferred Trust & GoldStar custodians
  • No card payments, no pressure, no commissions-first pitch

Stocks

Ownership — growth, real drawdowns

Bonds

A promise — income, credit and rate risk

Gold

No promise — no income, no default

Why mix

They fail in different conditions

Three different things, not three horses in one race

A share is part-ownership of a business: it can compound over decades and it can fall by half in a year. A bond is a promise to pay: it produces contractual income and carries the risk that rates rise or the borrower disappoints. Gold is a metal: no income, no promise, and no issuer that can fail. Comparing them on return alone hides the thing that matters — each one breaks in different weather.

  • Stocks: growth engine, drawdown risk, dividend income
  • Bonds: contractual income, interest-rate and credit risk
  • Gold: no counterparty, no income, price volatility
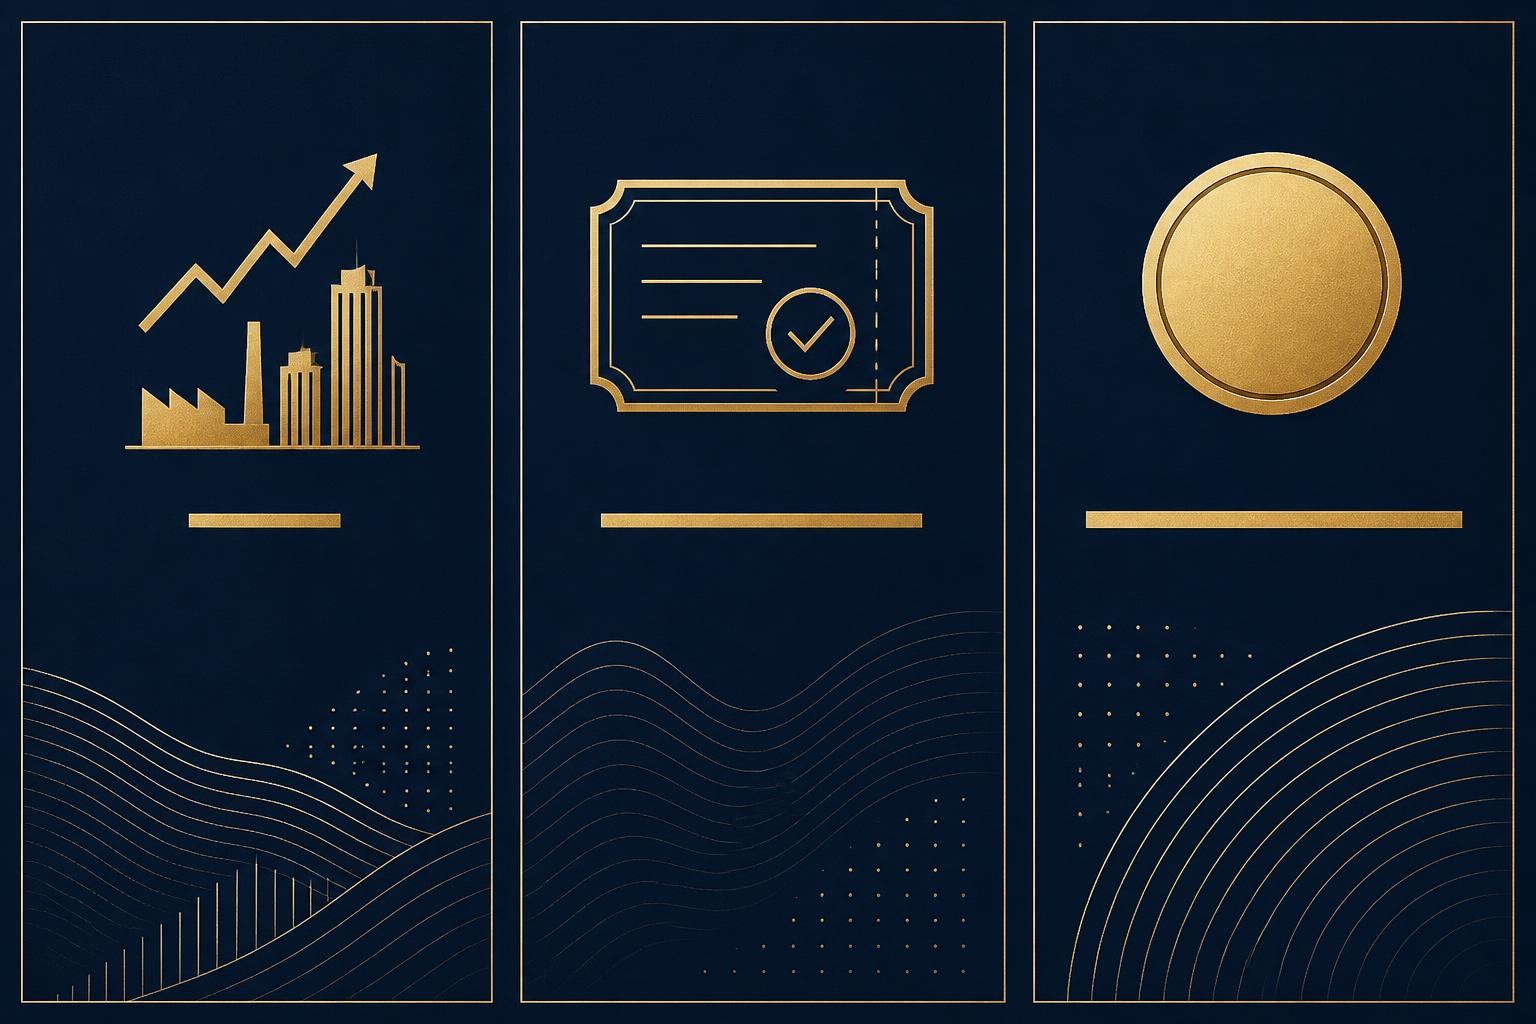
Three vertical navy panels, the first with a rising line above factory and tower silhouettes, the second with a certificate marked by regular ticks, the third with a plain gold disc
Shares own productive businesses, bonds own a payment schedule, gold owns nothing and promises nothing. Each fails in a different condition, which is the entire point of holding more than one.
Describe this illustration: Three vertical navy panels, the first with a rising line above factory and tower silhouettes, the second with a certificate marked by regular ticks, the third with a plain gold disc

An original Capstone Metals diagram of what each asset structurally is, rather than what each has recently returned. Equities are claims on company earnings and fall when earnings and confidence fall. Bonds are contracted payments and fall when rates rise or credit deteriorates. Gold produces nothing, pays nothing and has no issuer, so it is exposed to neither earnings nor credit — but it also has nothing working for it while you wait. A portfolio built on these differences survives conditions a return chart never showed.
Diagram showing three assets responding differently to the same economic shock, with arrows moving in opposite directions
Diversification means assets that fail in different weather — not assets that all rise together.
Describe this illustration: Diagram showing three assets responding differently to the same economic shock, with arrows moving in opposite directions

Diversification means assets that fail in different weather — not assets that all rise together. This original Capstone Metals diagram illustrates diagram showing three assets responding differently to the same economic shock, with arrows moving in opposite directions. It is educational artwork, not a price forecast, performance record or recommendation.
What diversification research actually supports

EXPERT ANALYSIS. Morningstar's portfolio work supports gold as a diversifier on the basis that it has behaved differently from equities and bonds, particularly during equity stress — while stating that its record must be measured over long holding periods and that it pays nothing meanwhile. OPINION. Ray Dalio's balanced-risk writing describes gold as one of the assets he considers inflation-hedging in a portfolio designed for several different economic environments; that is his stated method, not a study. INDUSTRY POSITION. The World Gold Council makes a fuller diversification case, and it is funded by gold miners.

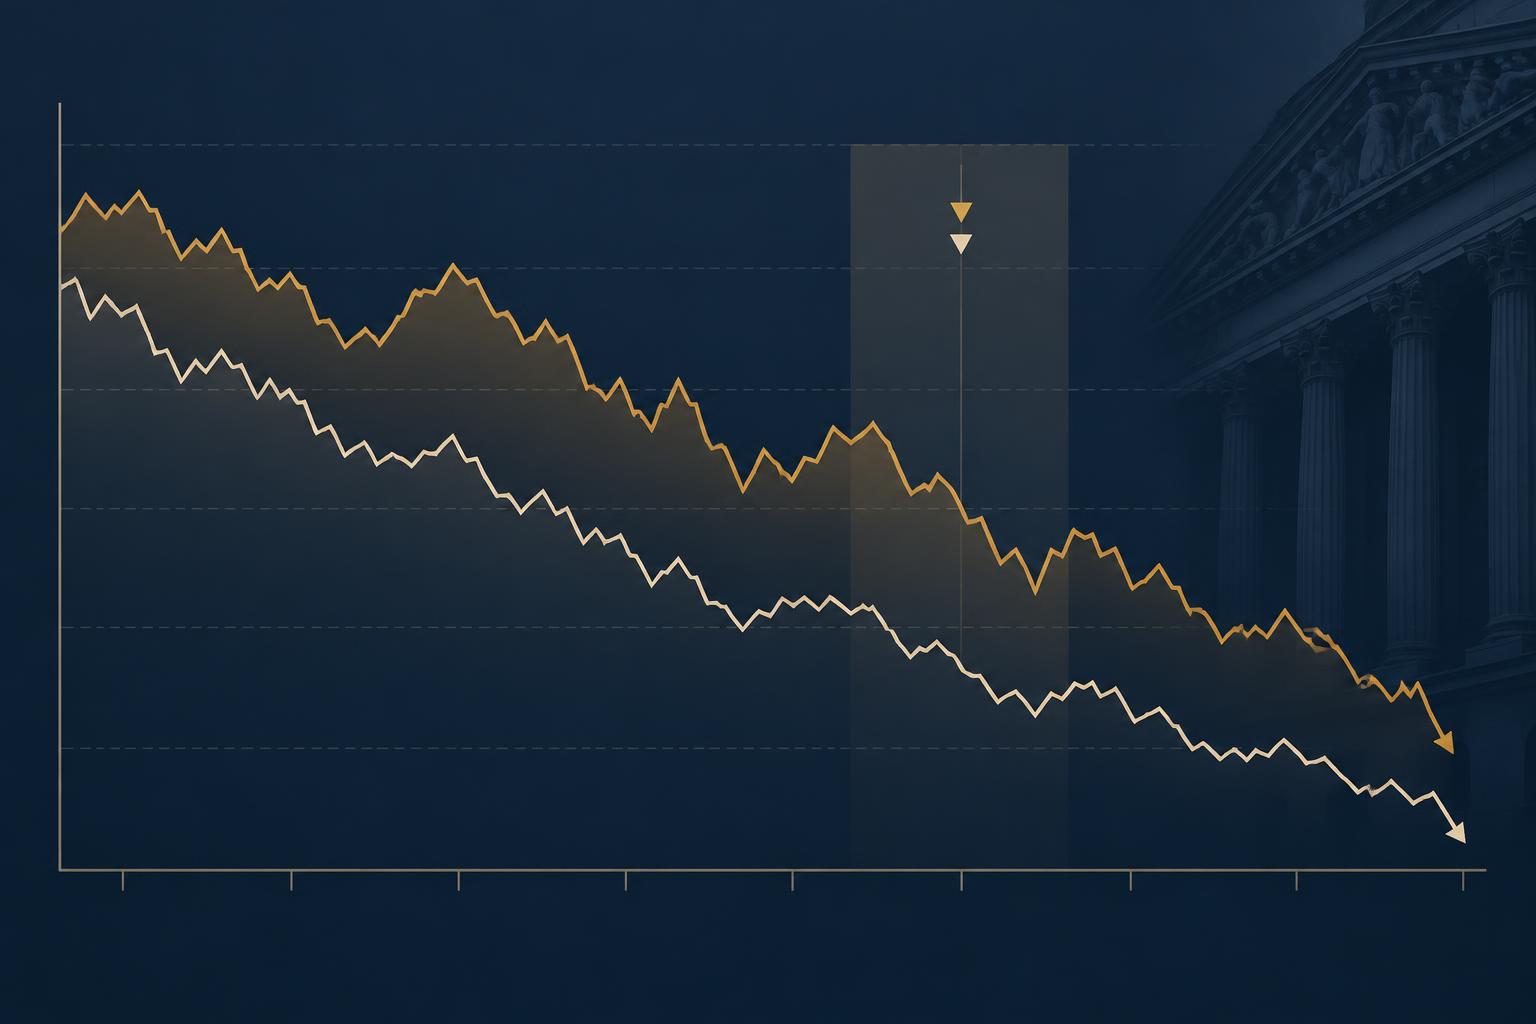
Line chart showing equity and bond indices declining in the same year
The year the bond cushion did not cushion — the reason structural difference is worth paying for.
Describe this illustration: Line chart showing equity and bond indices declining in the same year

The year the bond cushion did not cushion — the reason structural difference is worth paying for. This original Capstone Metals chart illustrates line chart showing equity and bond indices declining in the same year. It is educational artwork, not a price forecast, performance record or recommendation.
The 2022 lesson people actually remember

FACT. In 2022 stocks and bonds fell together, which undid the assumption that a bond allocation always cushions an equity decline. Gold's behaviour that year was mixed rather than heroic — not the rescue some marketing implies. The durable lesson is not that gold saved anyone; it is that two assets sharing one risk factor can disappoint at the same moment, which is precisely why structural difference is worth paying for.

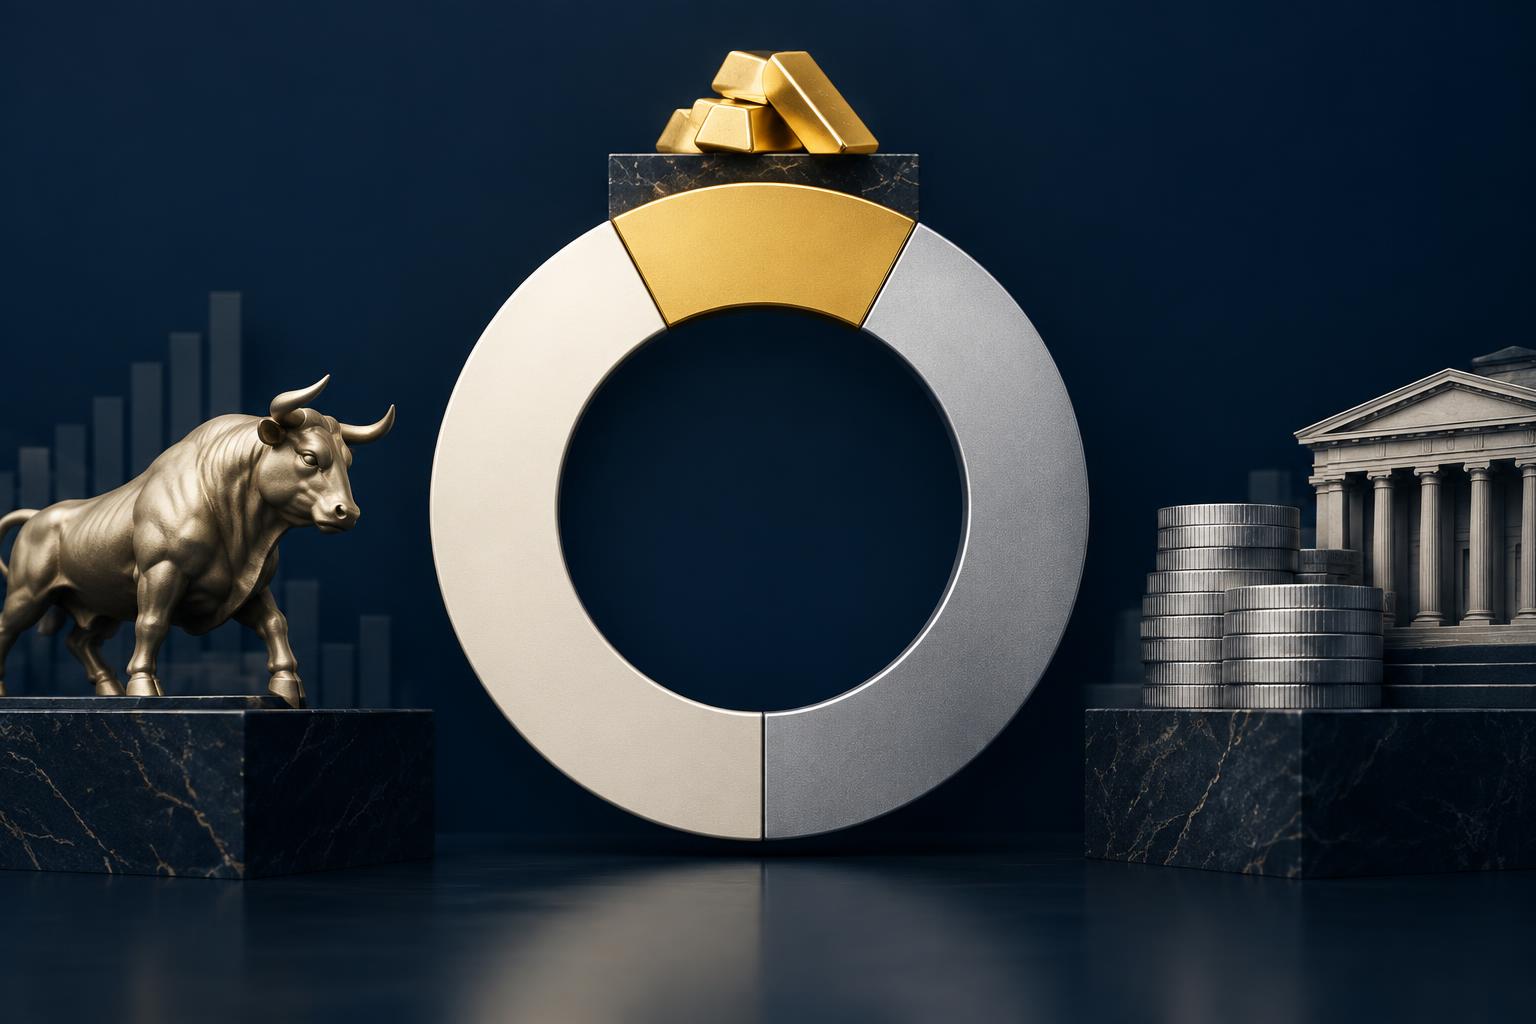
Portfolio ring diagram with a small metals segment labelled as ballast beside larger equity and bond segments
Metals are normally a minority ballast. Anyone urging you to move everything is selling, not advising.
Describe this illustration: Portfolio ring diagram with a small metals segment labelled as ballast beside larger equity and bond segments

Metals are normally a minority ballast. Anyone urging you to move everything is selling, not advising. This original Capstone Metals diagram illustrates portfolio ring diagram with a small metals segment labelled as ballast beside larger equity and bond segments. It is educational artwork, not a price forecast, performance record or recommendation.
Where this comparison misleads

Gold is not a substitute for growth. A portfolio with no ownership of productive businesses is unlikely to fund a long retirement, and a portfolio with no income has to sell something to pay bills. Metal is normally a minority ballast, and most people who add it move a portion of one account rather than restructuring everything. Anyone urging you to move it all is selling, not advising.

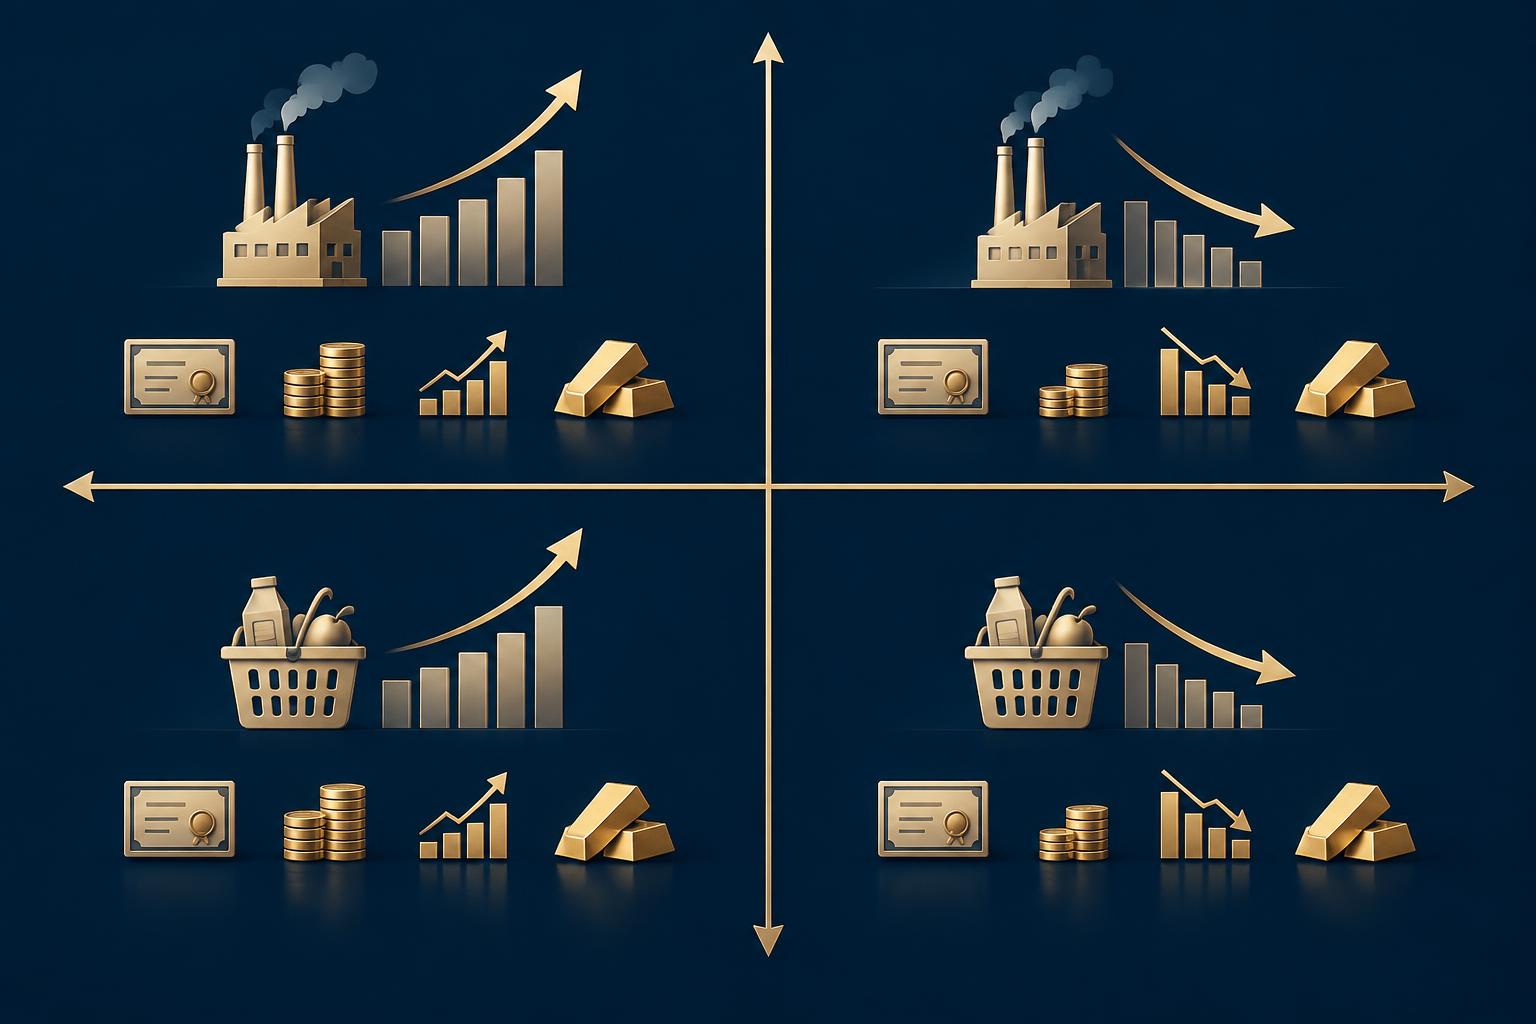
Quadrant diagram of rising and falling growth against rising and falling inflation, with asset types placed in each quadrant
One published way of thinking about balancing risk across environments — a method, not a recommendation.
Describe this illustration: Quadrant diagram of rising and falling growth against rising and falling inflation, with asset types placed in each quadrant

One published way of thinking about balancing risk across environments — a method, not a recommendation. This original Capstone Metals diagram illustrates quadrant diagram of rising and falling growth against rising and falling inflation, with asset types placed in each quadrant. It is educational artwork, not a price forecast, performance record or recommendation.
What the research does NOT say

It does not say gold outperforms stocks or bonds, that any fixed percentage is correct, or that diversification prevents losses. Diversification changes how a portfolio fails; it does not stop it falling. And no cited source endorses Capstone, gold IRAs or any product.

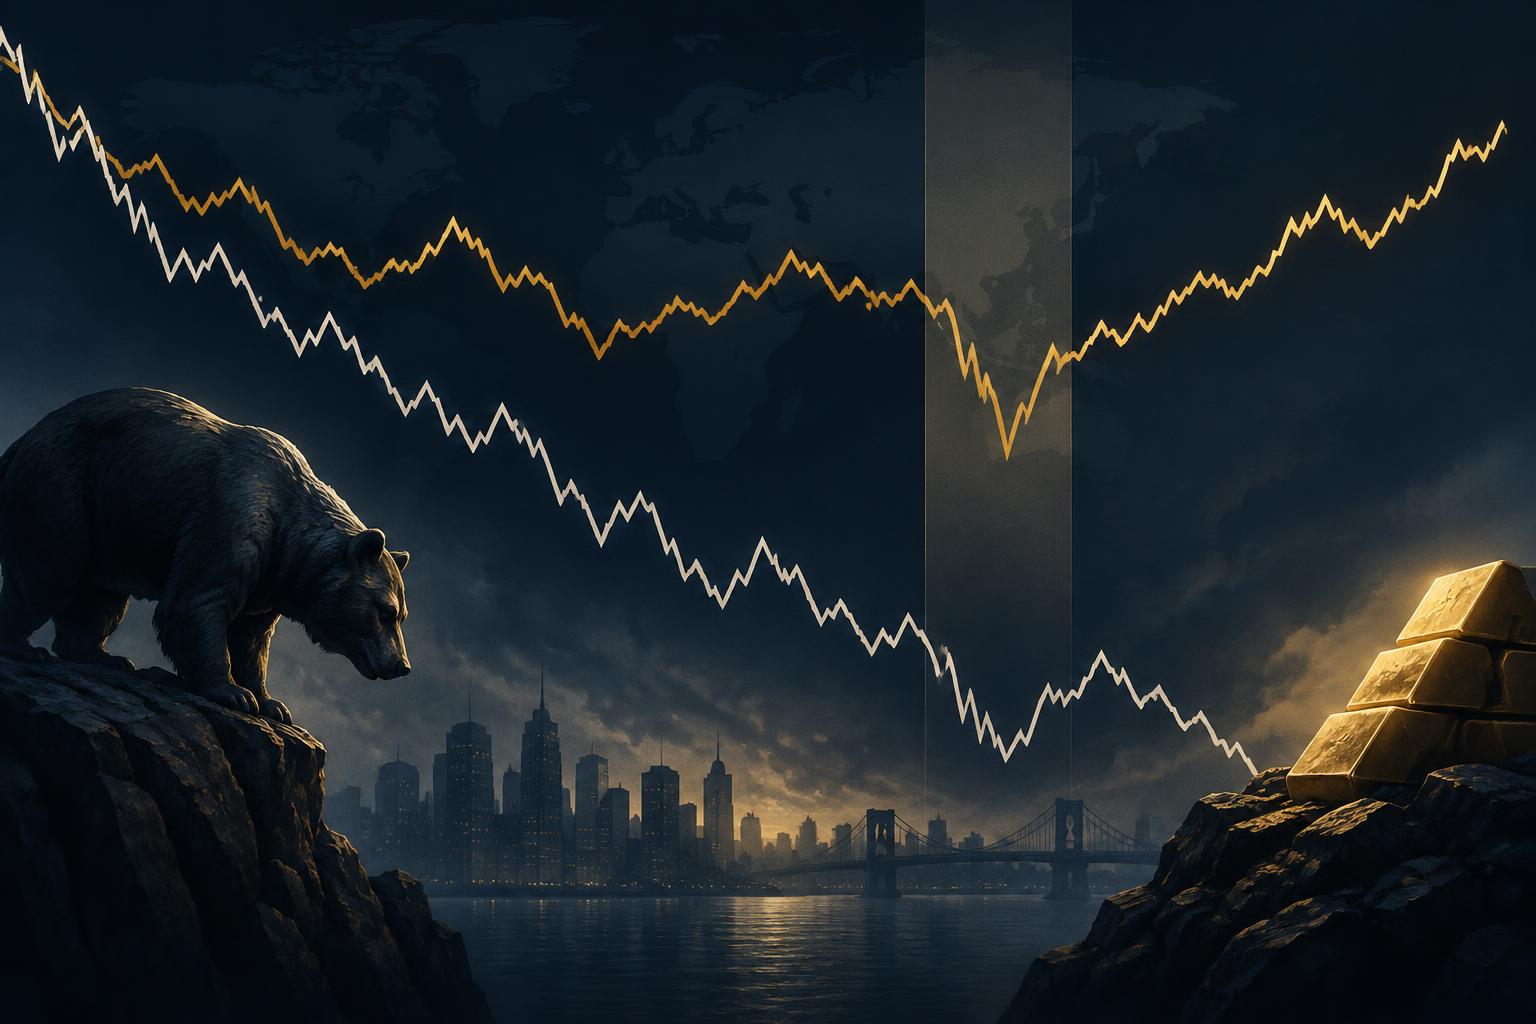
Illustration of an equity index falling steeply while a gold line moves independently, with a note marking one period where both fell
Different, not opposite — and in liquidity events, sometimes not different at all.
Describe this illustration: Illustration of an equity index falling steeply while a gold line moves independently, with a note marking one period where both fell

Different, not opposite — and in liquidity events, sometimes not different at all. This original Capstone Metals illustration illustrates illustration of an equity index falling steeply while a gold line moves independently, with a note marking one period where both fell. It is educational artwork, not a price forecast, performance record or recommendation.

Visual research library

More visual explanations

Illustration of a household balance sheet spread across a table with retirement accounts, insurance and metals shown together
One review of everything owned, rather than a sales call about one product.
Describe this illustration: Illustration of a household balance sheet spread across a table with retirement accounts, insurance and metals shown together

One review of everything owned, rather than a sales call about one product. This original Capstone Metals illustration illustrates illustration of a household balance sheet spread across a table with retirement accounts, insurance and metals shown together. It is educational artwork, not a price forecast, performance record or recommendation.

Rather just ask someone?

A specialist can answer this in two minutes. Monday – Friday, 7am – 4pm Pacific.

The short answer

Stocks are ownership of productive businesses, bonds are a promise to pay, and gold is neither — it produces no income but carries no counterparty, which is why the three fail in different conditions and why research treats gold as ballast rather than as a growth engine.

Key facts

Each fact below is tied to a numbered source at the foot of this page. Follow the numbers and check us.

  1. 01

    The IMF states that gold carries no credit risk but is volatile, and that its hedging and diversification benefits are conditional rather than automatic.1

    The Fund's July 2026 note on gold in central bank reserves is the most useful counterweight to industry advocacy: it accepts why reserve managers hold gold and then sets out plainly where the protection does not hold.

  2. 02

    The U.S. Geological Survey describes gold as a long-term store of value with a historical monetary role.2

    A government minerals agency with no commercial interest in the gold trade states the physical and historical facts: durable, divisible, scarce, and used as money long before it was an investment.

  3. 03

    Independent research supports gold as a diversifier while stating its limitations in the same breath.6

    Morningstar sets out its behaviour during equity stress alongside the long holding periods involved, its volatility, and the absence of income.

  4. 04

    Gold pays no interest and no dividend.5,6

    The entire return depends on the price when it is sold, so a long flat period has a genuine opportunity cost on top of storage or depository fees.

  5. 05

    In 2022, stocks and bonds fell together.1,2,4,5,6

    The assumption that a bond allocation always cushions an equity decline failed in that year, which is why structural variety — not just a second asset class — is the point of diversification.

  6. 06

    Ray Dalio identifies gold among the inflation-hedging assets in his balanced-risk framework.8,9

    That is his own stated method for building a portfolio across different economic environments — one investor's approach, published under his name, not a study.

The vocabulary

Drawdown
The fall from a previous peak to a later low, and how long it lasts. It matters more than average returns to anyone who might need the money during it.
Real interest rate
The interest rate after inflation. When it is deeply negative, holding a non-yielding asset costs less in relative terms; when it is high, the opportunity cost of gold rises.
Primary source
The original document — a statute, an official statistic, a central bank publication — rather than an article describing it. Every claim on this site is meant to trace back to one.
Diversification
Holding assets that behave differently so a portfolio does not depend on one outcome. It changes how a portfolio fails; it does not prevent losses.
Ballast
A holding kept for stability rather than growth, normally a minority of a portfolio.

Risks and limitations

Anyone who only tells you the upside is selling, not explaining.

  • No growth engine

    A portfolio without ownership of productive businesses is unlikely to fund a long retirement.

  • No income to spend

    A portfolio of non-income assets must be sold to pay bills.

  • Correlation surprises

    Assets can fall together in liquidity events, gold included. Diversification is not a guarantee.

Common misconceptions

Central banks are buying, so the price must rise.

Official demand is one input among many, and it is already known to the market. Reserve managers buy for reserve-management reasons on multi-decade horizons, which says nothing reliable about the next year's price.

Gold beats stocks over the long run.

They do different jobs and the comparison depends entirely on the start and end dates chosen. Equities have been the long-run growth engine; gold produces nothing.

These institutions recommend gold IRAs, or recommend Capstone.

None of them has any relationship with Capstone Metals and none comments on any dealer. Citing a public document is not an endorsement, and no page here may imply it is.

Mistakes worth avoiding

  • Choosing between the three instead of deciding what each is for
  • Moving an entire account into one asset
  • Comparing performance from a start date chosen to flatter the answer

What people ask next

Sources and references

Everything factual on this page traces to one of the following. Law and government publications come first, then exchange specifications and standards bodies.

  1. 1.
    Gold in central bank reserves: strategic considerations, market risks, and practical guidance

    International Monetary Fund · Tier 1 Primary / government · Expert analysis · published 2026-07 · checked 2026-09-15

    An IMF note written for reserve managers. It records that gold features prominently in official reserves and carries no credit risk, and it is equally direct that gold is volatile and that its hedging and diversification benefits depend on conditions rather than holding in all circumstances. It is the central counterweight to industry advocacy in this cluster.

  2. 2.
    Gold statistics and information

    U.S. Geological Survey · Tier 1 Primary / government · Reported data · checked 2026-09-15

    The federal minerals agency's gold page: physical properties, industrial and investment uses, and production and supply statistics, alongside a description of gold's historical monetary role. Government data with no commercial interest in the metal.

  3. 3.
    2026 gold and gold equity outlook

    BlackRock · Tier 2 Industry / authoritative · Forecast — not a fact · published 2026 · checked 2026-09-15

    The world's largest asset manager setting out its house view on gold and gold mining equities, framed around currency debasement concerns, fiscal deficits and geopolitical risk. It is a forward-looking house view from a firm that manages gold-linked funds, not a measurement.

  4. 4.
    Taking stock of the gold rally

    Bridgewater Associates · Tier 2 Industry / authoritative · Expert analysis · checked 2026-09-15

    Institutional analysis of the recent gold rally, examining gold's role in portfolios and what its repricing against fiat currencies may indicate about the monetary regime. It is argued analysis about causes, not a measurement and not a forecast of what happens next.

  5. 5.
    Is it too late to invest in gold and silver?

    Fidelity · Tier 2 Industry / authoritative · Expert analysis · published 2026-03-25 · checked 2026-09-15

    Fidelity's educational piece on precious-metals exposure, covering the different ways an investor can obtain it and the volatility involved. It states directly that short-term price movements are unpredictable, a caution worth carrying into any decision.

  6. 6.
    How to use gold in your portfolio

    Morningstar · Tier 2 Industry / authoritative · Expert analysis · published 2026-05-19 · checked 2026-09-15

    Independent investment research on what gold has and has not done inside a portfolio, including its diversification behaviour, its volatility and the long holding periods over which its record is measured. Notably, it states the counterpoints as plainly as the case for holding it.

  7. 7.
    The relevance of gold as a strategic asset

    World Gold Council · Tier 2 Industry / authoritative · Industry position — has a commercial interest · checked 2026-09-15

    The gold industry's own annual argument for holding gold as a strategic portfolio asset, resting on diversification, deep liquidity and long-run return history. The World Gold Council is funded by gold mining companies, so this is an industry position rather than independent research, and it should be read alongside sources that state gold's limitations.

  8. 8.
    March 2019 newsletter

    Lyn Alden · Tier 3 Reputable secondary · Opinion · published 2019-03 · checked 2026-09-15

    A 2019 newsletter in which an independent analyst discusses model portfolios that include precious-metals exposure. It is cited here strictly as a historical example of how allocation has been discussed publicly; it is seven years old and is not current allocation guidance.

  9. 9.
    The concept and mechanics of an All Weather portfolio

    Ray Dalio · Tier 3 Reputable secondary · Opinion · published 2026-03-23 · checked 2026-09-15

    Ray Dalio describes how he thinks about balancing risk across assets that behave differently in different economic environments, identifying gold among the inflation-hedging assets in that framework. It is one investor's stated method, written by him, not a study.

Who wrote and reviewed this

Written by
Travis Bugli
Chief Executive Officer and licensed agent, Capstone Metals
Reviewed by
Mark Bugli
Senior Advisory Partner, licensed since 1970
First published
2026-09-15
Last reviewed
2026-09-15
Change log (1)
  • 2026-09-15

    Published as a structural comparison rather than a performance chart, including the 2022 stock-and-bond decline.

    Why: Structure explains how assets fail; past returns do not.

This page explains general rules and mechanics. It is not individualised tax, legal or investment advice, and Capstone Metals is a precious-metals dealer rather than a custodian, trustee or depository. Confirm eligibility for any specific product with your IRA custodian, and discuss suitability with your own advisers.

Would a short, no-pressure conversation help?

Leave your name and number. A Capstone specialist will answer your questions during business hours.

Most gold and silver firms can only talk to you about gold and silver. We have licensed advisors on staff, so the same conversation can cover your retirement accounts, your market holdings, insurance and estate structure alongside a completely private metals purchase — one fiduciary review of everything you own, not a sales call about one product.

What would you like help understanding? (optional)

By submitting your name and phone number you are asking us to follow up, and you agree that Capstone Metals may contact you by phone, text, or email to clarify what you are looking for and make sure you receive it. Message and data rates may apply. You can ask us to stop at any time by replying STOP or telling us on the phone, and we never sell or share your information. This is a request for information and a conversation — not a purchase, an application, or advice. SMS Opt-In Policy · Privacy Policy · Terms & Conditions · How pricing works · Disclosures · Due diligence & financial risks

Licensed and insuredFiduciary advisory since 1970Independent IRA custodiansPrices quoted, never card-charged

Want a number rather than a conversation first? Request current gold pricing — itemized spot reference and premium, with the research and its limits sent afterwards.

Common questions

Is gold better than stocks?
They do different jobs, so “better” does not apply. Stocks are ownership of productive businesses and have driven long-run growth; gold produces nothing but carries no counterparty. Most portfolios need the first and use the second, if at all, as ballast.
Is gold better than bonds?
A bond pays contractual income and carries credit and interest-rate risk; gold pays nothing and carries neither. In 2022, when stocks and bonds fell together, the limitation of relying on bonds alone as a cushion became visible — which is an argument for structural variety, not for abandoning bonds.
How much gold belongs in a diversified portfolio?
Research discusses ranges rather than a single answer, and disciplined frameworks generally treat metals as a minority ballast rather than a core holding. The right figure depends on your income needs, time horizon and other holdings.
How allocation is thought about
Does gold protect against a stock market crash?
It has behaved differently from equities during periods of equity stress, which is what diversification means — but it has also fallen alongside other assets in liquidity events. It is not insurance and no research treats it as such.
Worked scenarios with the arithmetic shown
Can I hold all three in a retirement account?
Broadly yes — stocks and bonds in an ordinary IRA or employer plan, and IRS-eligible bullion through a self-directed IRA with an approved custodian and depository. Many households keep both, moving only a portion.
How a gold IRA works
Is gold right for everyone?
No. Anyone carrying high-interest debt, without an emergency reserve, or likely to need the money within a few years is usually better served by fixing those things first. Gold is a minority holding for money that can sit still, and we will say so on the phone.
Does adding gold reduce portfolio risk?
Research supports it behaving differently from equities and bonds, which can reduce how much a portfolio moves as a whole. It does not remove risk, and too large a position introduces concentration risk of its own.
Do I need bonds if I hold gold?
They are not substitutes. Bonds pay contractual income and carry credit and rate risk; gold pays nothing and carries neither. Most portfolios that hold gold hold bonds as well.

Have the whole portfolio looked at, not just the metal

Leave your name and a phone number. Because there are licensed financial advisors on staff, the review can cover retirement accounts, market holdings and insurance together — not metals in isolation.

Licensed and insuredFiduciary advisory since 1970Independent IRA custodiansPrices quoted, never card-charged
Call (800) 200-9553 Text Email